Does Direct Air Capture Make Money?
Not yet, and not as a merchant business. On the public numbers in 2026, direct air capture earns from three stacked sources: a 45Q tax credit worth 180 dollars a tonne for permanent storage, multi-year credit sales to a very small set of buyers, and a sponsor balance sheet patient enough to carry a plant to nameplate. Microsoft alone accounted for about 93 per cent of all carbon removal credits bought globally in 2025. A business with one customer is not yet a market, and that, rather than the engineering, is what decides whether direct air capture makes money.
- The 45Q credit for direct air capture with permanent geologic storage is 180 dollars per tonne, maintained for 2024 to 2026 and inflation-adjusted for projects beginning after the start of 2027.
- The One Big Beautiful Bill Act, signed 4 July 2025, gave utilisation and enhanced oil recovery parity with the higher storage value. For direct air capture that lifted the enhanced oil recovery route from 130 dollars toward the storage rate, which materially changes project economics for an operator that already has Permian injection capacity.
- Transferability survived, so credits can be sold for cash rather than used against the developer's own tax bill. Restrictions now apply to specified foreign entities from taxable years beginning after 4 July 2025, and to foreign-influenced entities after 4 July 2027.
- The voluntary market is dangerously concentrated. Microsoft bought about 93 per cent of all carbon removal credits globally in 2025, on BloombergNEF and Business Council for Sustainable Energy figures published in February 2026, within total demand of roughly 57 million tonnes.
- Price expectations and budgets have not met. The CDR.fyi and OPIS pricing survey published on 7 May 2026 found the average buyer-supplier spread narrowing from 107 dollars to 98 dollars a tonne, with respondents expecting 48 dollars by 2030 and the report judging that durable credits are unlikely to broadly reach 100 dollars a tonne by 2030. Sixty five per cent of buyers named budget constraints as their main blocker.
- Stratos is the test case and is not yet proving the thesis. Designed for up to 500,000 tonnes a year on a 65 acre site, with Class VI permits secured in April 2025 and the second 250,000 tonne phase complete, it was still being described as under construction, with a non-process facility issue under evaluation as of the first quarter 2026 call.
- Occidental's balance sheet moved in the other direction. It completed the 9.7 billion dollar sale of OxyChem to Berkshire Hathaway on 2 January 2026, which chief executive Vicki Hollub said accelerates the strategy to strengthen the balance sheet. Carbon management is being funded by a company deleveraging, not by carbon management's own cash flows.
- The honest summary: the technology is becoming investable, in Hollub's 2023 phrase, but investable is not the same as profitable, and nothing in the 2026 public record closes that gap.
A tax credit, an offtake and a sponsor, and all three have to be present
There is no commodity price for removed carbon dioxide. A direct air capture plant therefore does not sell a product into a liquid market. It assembles a revenue stack, and each layer has a different counterparty and a different failure mode.
Layer one is Section 45Q. For direct air capture with permanent geologic storage the credit is 180 dollars per metric tonne, a value maintained for 2024 to 2026 under the One Big Beautiful Bill Act signed on 4 July 2025, with inflation adjustment applying to projects beginning after the start of 2027. The Act also made permanent storage, utilisation in secondary products and enhanced oil recovery qualify for the same higher value, where direct air capture routed to enhanced oil recovery had previously earned 130 dollars. Credits remain transferable, so a developer without sufficient tax appetite can sell them for cash, subject to new restrictions on specified foreign entities from taxable years beginning after 4 July 2025 and on foreign-influenced entities after 4 July 2027.
Layer two is the sale of carbon removal credits to corporate buyers. This is the layer everyone assumes is the business, and it is the weakest of the three.
Layer three is the sponsor. Somebody has to fund construction, commissioning and the period before nameplate output, against revenue that does not yet exist. At Stratos that was Occidental alongside a 550 million dollar investment by BlackRock, made on behalf of clients through a fund managed by its Diversified Infrastructure business, announced on 7 November 2023.
Remove any one layer and the project does not clear. That is the real answer to whether direct air capture makes money: it does not make money, a stack makes money, and the stack is currently held together by public policy at one end and a handful of corporate balance sheets at the other.
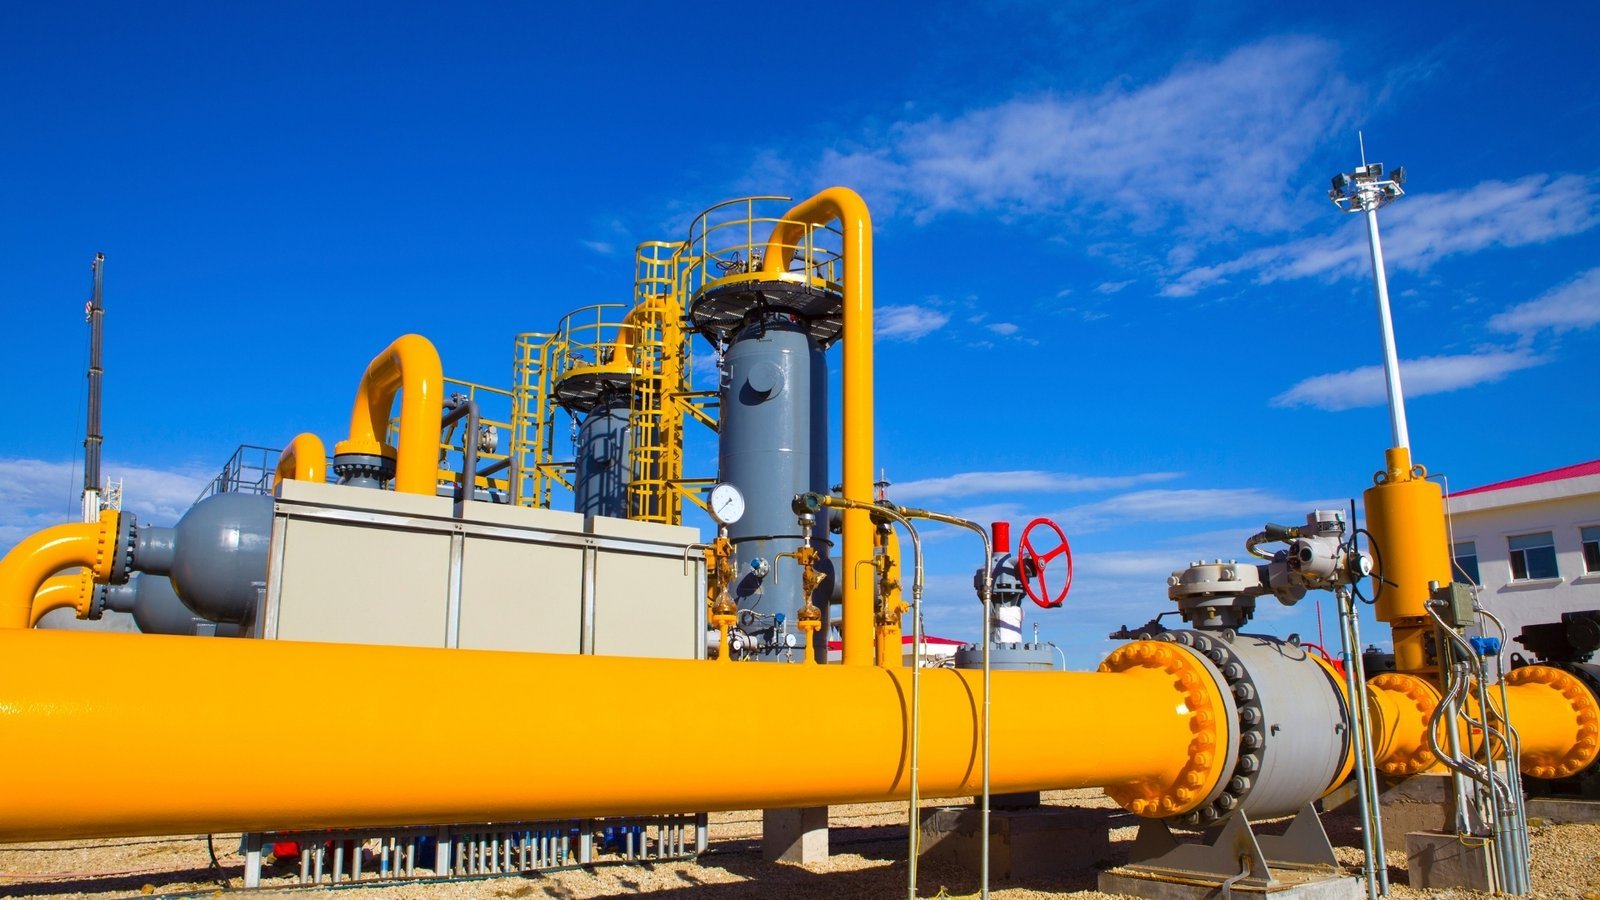 المشروع 54Gas handling and injection infrastructure. Direct air capture earns from a tax credit, an offtake and a sponsor balance sheet, not from a commodity price for the carbon dioxide it moves.
| Revenue layer | What it pays | Counterparty | Principal risk |
|---|---|---|---|
| 45Q, permanent geologic storage | 180 dollars per tonne, inflation-adjusted for projects beginning after start of 2027 | US federal government, via tax credit or credit transfer | Political durability; foreign entity restrictions; qualification and measurement |
| 45Q, utilisation and enhanced oil recovery | Parity with the storage value under the One Big Beautiful Bill Act, up from 130 dollars for direct air capture | Same | Same, plus reputational exposure to the enhanced oil recovery route |
| Carbon removal credit sales | Not publicly disclosed per contract | A very small set of corporate buyers | Single-buyer concentration; budget constraints; price expectations well below supplier costs |
| Sponsor equity and partner capital | Funds construction and the pre-nameplate period | Operator and infrastructure investors | Cost overrun; schedule slip; competing calls on the sponsor's capital |
Because it is effectively one buyer
BloombergNEF and the Business Council for Sustainable Energy, in research published in February 2026, found that Microsoft bought about 93 per cent of all carbon removal credits globally in 2025, the first year the groups tracked market demand. Total global demand was about 57 million tonnes, roughly double 2024.
A market where one buyer accounts for more than nine credits in every ten is not a market in any sense a project financier would recognise. It is a bilateral relationship with extra steps. Every supplier's price discovery, volume planning and credit risk analysis collapses into a single question: what will that one buyer do next year.
Microsoft itself has not signalled retreat. Phil Goodman, who directs Microsoft's carbon removal portfolio, has said the company is still buying carbon dioxide removal in pursuit of its carbon-negative goal, and that AI does not change its sustainability goals. Brian Marrs, who leads the company's energy and carbon removal work, has argued that hyperscalers may need carbon removal to backstop 2030 net zero targets. Those are reassuring statements and they do not fix the structural problem, which is that a supplier cannot underwrite a 500,000 tonne a year asset against one customer's continued enthusiasm.
Pricing tells the same story from the other side. The second annual CDR.fyi and OPIS pricing survey, published on 7 May 2026, found the average spread between what buyers will pay and what suppliers want fell from 107 dollars a tonne to 98 dollars a tonne, with respondents expecting it to reach 48 dollars by 2030. The report judged that durable carbon removal credits are unlikely to broadly reach 100 dollars a tonne by 2030. Sixty five per cent of buyers named budget constraints as their main blocker.
Put the two together. A persistent gap of roughly 98 dollars a tonne between buyer and seller, in a market where one buyer sets the clearing level, against a technology whose unsubsidised cost no operator has published. That is the gap the 180 dollar credit is carrying.
Built, largely commissioned, not yet proving the economics
Stratos sits on a 65 acre site in Ector County, Texas, and is designed to capture up to 500,000 tonnes of carbon dioxide a year once fully operational. It was developed by 1PointFive, an Occidental subsidiary, in a joint venture formed with BlackRock, which invested 550 million dollars on behalf of clients, announced on 7 November 2023 when construction was around 30 per cent complete. Class VI injection well permits were secured in April 2025. About 2,500 construction workers were hired during Phase I, and over 800 craft workers took part in an apprenticeship programme run by the engineering contractor Worley.
On the company's first quarter 2026 results call, reported on 8 May 2026, incoming chief executive Richard Jackson said the technology and process unit operations had performed as expected during commissioning, and that the company had identified an issue related to non-process components of the facility, unrelated to the technology. He said Occidental was evaluating the repair timeline and assessing the impact on the operations schedule, with an update due the following quarter, and that the issue was not currently expected to affect 2026 capital spending guidance. Phase 2, the second 250,000 tonne a year phase including the final two air contactor trains and updated pellet reactors, was reported complete.
1PointFive's own project page still describes the facility as currently under construction and names Microsoft, Amazon, ANA and Bain & Company among early adopters of Stratos carbon removal credits. Earlier announcements had also named Airbus, TD Bank Group, the Houston Astros and the Houston Texans as credit purchasers. No contract volumes or prices are disclosed.
Note what is not in the public record. Occidental has not disclosed a capture cost per tonne for Stratos, nor the price at which credits have been sold, nor the project's expected return. Any per-tonne cost figure circulating for Stratos is an outside estimate, and should be labelled as one in any document you put in front of a board.
Vicki Hollub's framing when the BlackRock joint venture was announced remains the fairest description of where the project sits: the joint venture demonstrates that direct air capture is becoming an investable technology. Investable is a claim about access to capital. It is not a claim about profit, and three years on it still is not one.
From selling a profitable chemicals business, not from carbon
On 2 January 2026 Occidental completed the sale of OxyChem to Berkshire Hathaway for 9.7 billion dollars in cash, subject to customary purchase price adjustments. Vicki Hollub said the deal accelerates the strategy to strengthen Occidental's balance sheet.
That transaction is the most informative single data point about direct air capture economics in 2026, and it is not about direct air capture at all. A company that is simultaneously operating the world's largest direct air capture facility chose to raise nearly ten billion dollars by divesting a cash-generative chemicals business in order to reduce debt.
The reading is not that carbon management has been abandoned. It is that carbon management is a call on capital rather than a source of it, and that the sponsor is strengthening the balance sheet that has to carry it. For anyone modelling a direct air capture project, the implication is that sponsor credit quality belongs in the model as a first-order variable, not a footnote.
We set out the wider strategic logic of Occidental's two bets, Permian oil and carbon management, in a separate dossier, and the Stratos facility itself in another.
Four conditions, three of which are commercial rather than technical
First, buyer diversification. The single most valuable development for this industry would be a second and third buyer of Microsoft's scale, or government procurement at comparable volume. Industry advocates have argued for exactly that. Until it happens, every supplier's business plan contains the same undiversified counterparty.
Second, cost falling to meet price rather than price rising to meet cost. The CDR.fyi and OPIS respondents expect the buyer-supplier spread at 48 dollars a tonne by 2030, which implies most of the convergence coming from the supply side. That is a cost reduction programme of a scale that has not yet been demonstrated in operation, which is why the second phase of Stratos incorporating design innovations from the Carbon Engineering Innovation Centre matters more than its incremental tonnes.
Third, policy durability. A 180 dollar credit maintained for 2024 to 2026 with inflation adjustment from 2027 is attractive and is also a political variable. Projects with twenty year lives are being underwritten by an instrument that has been revised more than once this decade. Any model should test the downside case of a materially reduced credit in the 2030s, and should note that foreign entity restrictions have already narrowed who can hold or receive these credits.
Fourth, demonstrated sustained operation at nameplate. Not a startup, not a commissioning milestone, but a year of audited tonnes at or near 500,000. Everything in the commercial case, from unit cost to offtake confidence to financing terms for the next plant, is waiting on that number.
An estimate rather than a measurement, offered as such: on the public record as it stands in October 2026, the first direct air capture facility that can show a full year at nameplate with disclosed unit costs will reset this entire debate, and until one does, the honest answer to the question in the title remains no.
استمع وخذها معك
هل تفضل الاستماع إلى التسجيل الصوتي، أم تحتاج إلى العرض التقديمي للمراجعة الداخلية؟ يتوفر العرض التقديمي الكامل كحلقة بودكاست وعرض شرائح قابل للتنزيل.
Your board asks whether the company should sign a ten year carbon removal offtake with a direct air capture developer. What is the first thing you check?
الأسئلة المتكررة
One hundred and eighty dollars per metric tonne for direct air capture with permanent geologic storage, a value maintained for 2024 to 2026 under the One Big Beautiful Bill Act signed on 4 July 2025, with inflation adjustment applying to projects beginning after the start of 2027. The Act also gave utilisation in secondary products and enhanced oil recovery parity with that higher storage value, where direct air capture routed to enhanced oil recovery had previously earned 130 dollars.
Yes. The One Big Beautiful Bill Act preserved transferability, so a developer without sufficient tax appetite can sell 45Q credits to third parties for cash. The main change is restrictions on foreign entities of concern: credits cannot be claimed by or transferred to specified foreign entities for any taxable year beginning after 4 July 2025, or to foreign-influenced entities after 4 July 2027.
Very few organisations, which is the central commercial problem. BloombergNEF and the Business Council for Sustainable Energy found that Microsoft accounted for roughly 93 per cent of all carbon removal credits bought globally in 2025, within total demand of about 57 million tonnes. For Stratos specifically, 1PointFive names Microsoft, Amazon, ANA and Bain & Company among early adopters, and earlier announcements named Airbus, TD Bank Group, the Houston Astros and the Houston Texans. Volumes and prices are not disclosed.
No operator of a large facility has published one. Occidental has not disclosed a capture cost per tonne for Stratos, nor the prices at which its credits have been sold. Figures circulating publicly are third-party estimates and should be labelled as estimates. What is observable is the gap between buyers and sellers: the CDR.fyi and OPIS survey published on 7 May 2026 put the average spread at 98 dollars a tonne, down from 107 dollars, with respondents expecting 48 dollars by 2030.
Not at full commercial output on the latest public record. 1PointFive's project page describes the facility as currently under construction. On Occidental's first quarter 2026 results call, reported on 8 May 2026, incoming chief executive Richard Jackson said the technology and process unit operations had performed as expected during commissioning, but that an issue related to non-process components of the facility, unrelated to the technology, was being evaluated, with an update due the following quarter. The second 250,000 tonne a year phase was reported complete.
احصل على التالي إسقاط معلومات استخباراتية
انضم إلى قادة الطاقة والصناعة واحصل على معلوماتنا التسويقية، ونمو الذكاء الاصطناعي، وهيكلة الإيرادات، مباشرة وبدون حشو.
اسمك مدرج في القائمة
أهلاً بكم في موجز نمو الطاقة، تابعوا بريدكم الوارد للاطلاع على النشرة القادمة.