Selling Into a Supply Shock: What 110 Dollar Brent Changes
Most energy B2B commercial playbooks in use today were written for a cheap barrel. They assume the buyer's dominant question is cost, that lead times are a detail, and that availability can be promised without being proved. Brent at 110 US dollars, Asian LNG at 30 dollars per million British thermal units and record tanker rates have retired those assumptions inside eight months. This is what changes in pricing, messaging, demand generation and contracting when scarcity replaces cost as the organising anxiety of the buying committee.
- The regime changed in months, not years. Brent was 61.75 US dollars a year ago, peaked near 126 US dollars at the end of April 2026 and traded at 110.74 US dollars on 21 October, up 79 per cent year on year.
- The buyer's dominant fear moved from paying too much to not receiving at all. That single change reorders every tender scoring sheet in the sector.
- Lead time is now the scarce good, not price. A supplier who can prove delivery in 10 weeks beats one who quotes 8 per cent less and cannot.
- Freight and insurance have become first-order line items. Record tanker rates and a reported attack on an LNG tanker off Yemen on 18 October mean logistics assumptions written in 2025 are no longer safe to quote against.
- Fixed-price, long-validity quotations are now a balance sheet risk. Shorten validity windows and index what you cannot control instead of absorbing it silently.
- Availability claims must become evidence. In a scarcity market, an unverifiable promise of supply is treated by procurement as a red flag rather than a differentiator.
- Demand generation should move toward continuity, integrity, debottlenecking and security scope, which is where operator budget is actually moving.
- Do not mistake a risk premium for structural demand. ING described the market as pricing a significant risk premium given volatility, and premiums can unwind faster than they build.
An eight month regime change
A year ago the sector's commercial conversation was about discipline under a weak price. Brent was 61.75 US dollars. The dominant supplier narrative was cost per unit, consolidation and doing more with a smaller operator budget.
The Iran war began in late February 2026. Brent peaked near 126 US dollars at the end of April, settled around 102 US dollars by early October and was back at 110.74 US dollars on the morning of 21 October, according to حظ. That is a 79 per cent year on year move.
The stress is broader than crude. Asian LNG spot prices reached 30.4 US dollars per million British thermal units, the highest since December 2022 on Bloomberg figures, and Dutch TTF futures traded just below 88 euros per megawatt hour on ICE data, both reported by يورونيوز. US Energy Secretary Chris Wright put Gulf crude flows at about 80 per cent of pre-war levels, with refined products more constrained.
Logistics repriced with it. The same reporting cites record tanker freight rates, and UK Maritime Trade Operations recorded an LNG tanker coming under fire from a small boat off Yemen on 18 October. Aramco chief executive Amin Nasser, speaking in London on 5 October, described global oil stocks as scarily thin and said rebuilding them could take two years. We examine the producer side of that in Aramco's real product is redundancy.
For a commercial team the relevant fact is not any single number. It is that the operator's planning assumptions were rewritten mid-year, and almost every piece of sales collateral in the sector was written before that happened.
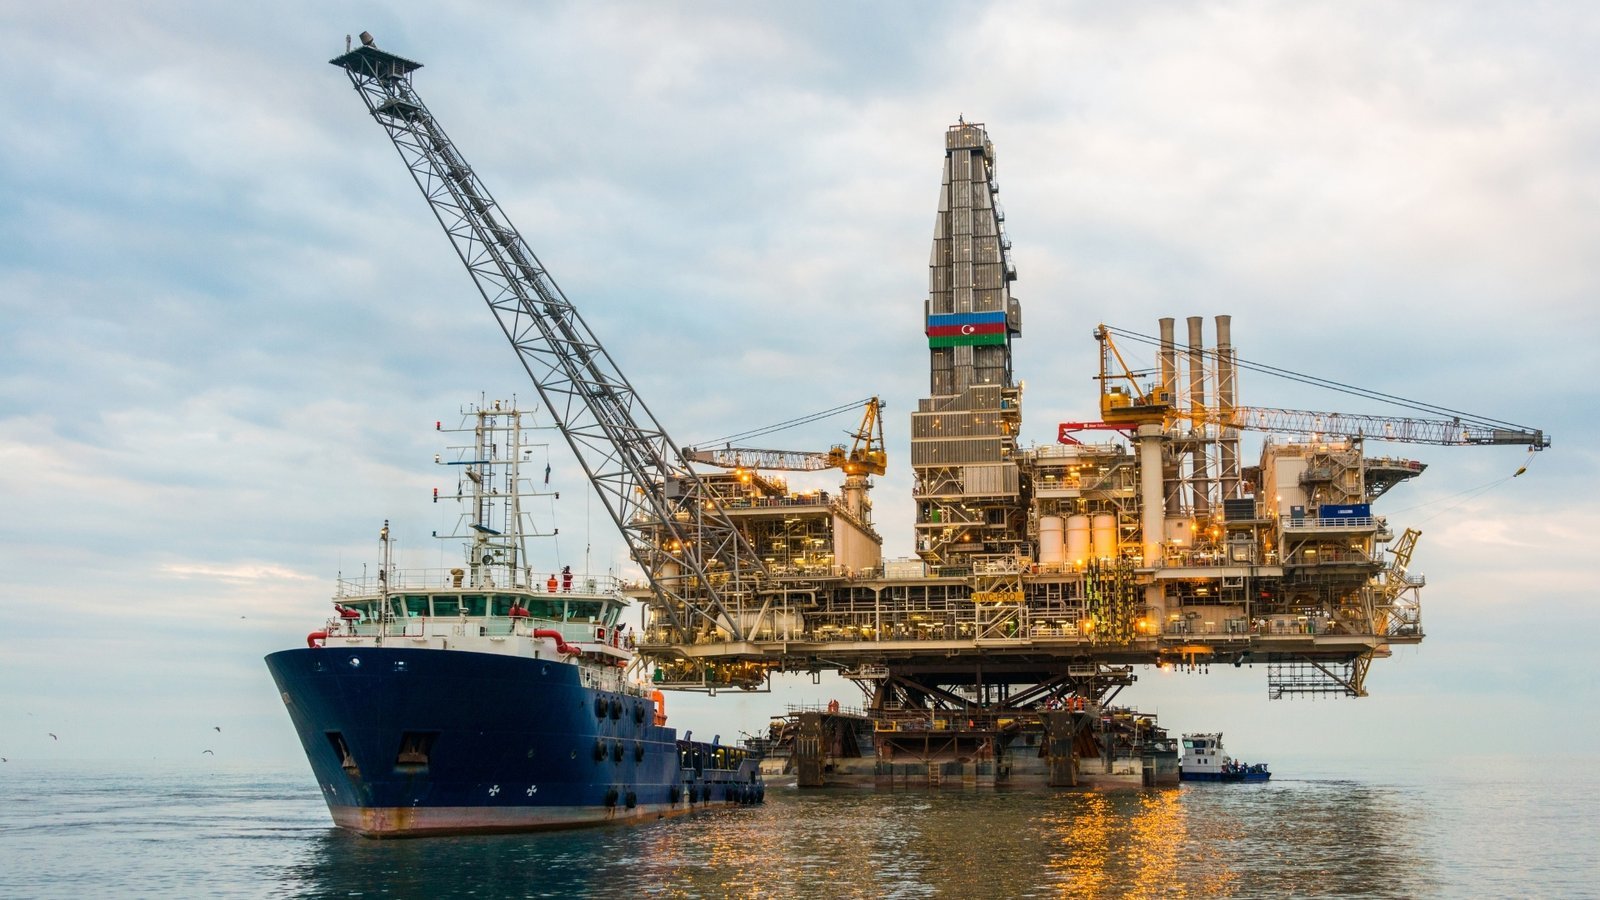 المشروع 54A jack-up drilling rig alongside a heavy lift vessel offshore. In a supply shock the scarce good is rarely the equipment. It is the certainty that it arrives on the promised date.
The committee is now managing a different risk
A procurement decision is a risk allocation dressed as a purchase. The buying committee's job is to minimise the risk that dominates at that moment, and the dominant risk has changed.
At 52 US dollars a barrel the dominant risk is commercial: overpaying, overcommitting, being caught with capacity nobody needs. The scoring sheet rewards the lowest compliant bid, because the downside being managed is financial.
At 110 US dollars with a contested export route, the dominant risk is operational: the plant stops, the cargo does not arrive, the turnaround overruns because a part is on a vessel that will not sail. The downside is no longer a bad price, it is an unproduced barrel priced at 110 US dollars. A buyer losing 110 dollars a barrel of production is structurally indifferent to an 8 per cent difference in the price of the part.
This is why the change is not simply that budgets loosen. The weighting changes. Delivery certainty, spares depth, local presence, response time and supply chain transparency move up the scoring sheet, and unit price moves down. A supplier organisation that has spent two years training its people to defend price has trained them for the previous question.
The practical test is simple. Ask your last five win-loss debriefs what the buyer said the deciding factor was. If your answers are all about price and your proposals are all about price, you are still selling into the old regime. Our method for running that review properly is in win-loss analysis for energy B2B tenders.
Stop quoting certainty you no longer own
The most common unforced error in a shock is continuing to issue the quotation format used in a stable market. A fixed price, held open for 60 or 90 days, covering freight, with a long delivery window, is a free option written against your own margin. The customer exercises it only if the market moves against you.
Four changes, in order of urgency. First, shorten quotation validity. In a market where tanker rates move weekly, 30 days is generous and 14 is defensible. Second, index what you do not control. Freight, insurance, energy input and currency are the usual candidates, and an indexed clause with a published reference is far easier to defend commercially than a silent margin absorption followed by a renegotiation request.
Third, separate the price of the product from the price of the delivery promise. Offering a standard lead time at one price and an expedited, guaranteed lead time at another turns scarcity into a product line rather than a source of conflict. Buyers in a shock will pay for certainty, but only if you have made certainty purchasable.
Fourth, read your force majeure clause before it is tested, not after. Clauses drafted in a calm market frequently fail to address route closure, insurance withdrawal or a carrier's refusal to transit. The time to agree what happens is while both parties are still relaxed about it.
Where relationships are long term, the shock is also the moment long-term agreements get reopened. Handle that deliberately rather than defensively: a renegotiation conducted early, with transparent indices, usually protects the relationship better than a surprise surcharge. The framework we use is in selling and structuring long-term agreements.
Follow the scope, not the sentiment
The temptation in a price spike is to produce commentary about the price spike. It generates traffic and almost no pipeline, because the operator reading it has no budget line called oil price. Follow the scope of work instead.
Budget in this regime moves toward four areas. Continuity and integrity work on assets that cannot be taken offline. Debottlenecking, because incremental capacity from an existing asset is the fastest barrel available. Security and resilience scope, physical and digital, on infrastructure that has become a target. And inventory and storage work, because an industry told it will spend two years rebuilding stock needs somewhere to put it.
Map your portfolio against those four, and lead with whichever you can prove. If you cannot credibly claim any of them, your fastest route is usually adjacency: the same product sold against a continuity outcome rather than an efficiency outcome, with the proof reassembled accordingly.
Rebalance channel spend toward the capture end. In a scarcity market a larger share of demand is already active and searching, so the return on well-structured technical and comparison content rises relative to broad awareness work. That is a shift in mix, not an abandonment of brand: the 95-5 logic still holds, and we set out why in the 95-5 rule in energy B2B.
One analytics warning. Shock conditions inflate impressions and traffic on anything topical, which produces a flattering dashboard and no revenue. Judge the shift on qualified pipeline by scope, not on sessions. We have written at length about that failure mode in search impressions are not demand.
| Commercial element | Cheap barrel regime | Shock regime |
|---|---|---|
| Buyer's dominant risk | Overpaying or overcommitting | Not receiving, or receiving late |
| Winning proposal emphasis | Lowest compliant price | Proven lead time and continuity |
| Quotation validity | 60 to 90 days, fixed | 14 to 30 days, indexed on freight and inputs |
| Lead time | A specification detail | The product itself, priced separately |
| Highest value proof | Cost case and references | Stock position, response time, route redundancy |
| Demand generation theme | Efficiency and cost per unit | Continuity, debottlenecking, integrity, security |
| Channel mix | Weighted to awareness | Weighted toward active capture, brand maintained |
| Biggest self-inflicted risk | Discounting to win | Treating a risk premium as structural demand |
Evidence, specificity and restraint
Every competitor is about to claim availability. The claim is therefore worth nothing, and in a market where buyers are genuinely exposed, an unverifiable promise reads as a risk rather than a benefit. Procurement teams have long memories for suppliers who promised during a shortage and failed.
Replace the claim with the evidence behind it. Stock held, and where. Current quoted lead time by product family, dated. Number of qualified sources per critical input. Vessel or freight arrangements already contracted. Recent delivery performance expressed as a percentage against promised dates. A single dated, specific, checkable number outperforms a page of reassurance.
Tone matters more than usual. Messaging that reads as monetising a conflict will be remembered by the same buying committee in the next cycle. The defensible posture is operational and plain: here is what we hold, here is what we can commit to, here is what we cannot. Restraint is also a differentiator when everyone else is shouting.
Get the proof into the formats procurement actually consumes. Prequalification packs, technical datasheets, capability statements and supplier portals carry more weight in this regime than campaign assets, because they are what gets read when a committee is deciding who is allowed to bid. Our guidance on assembling that is in supplier prequalification in energy B2B, and on getting the proof past confidentiality limits in proof assets under confidentiality.
Three failure modes, all expensive
The first is capacity built on a premium. A supplier reads 110 US dollar oil as a demand signal, hires, leases and commits, and the premium unwinds. ING's commodities strategists were explicit that prices at this level despite relatively strong flows suggest the market is pricing a significant risk premium given the volatility. A premium is a probability-weighted fear, and fear is not a backlog. Expand on contracted scope, not on spot price.
The second is silent margin absorption. Freight and insurance rise, the supplier swallows it to protect the relationship, and six months later arrives with a surcharge request and no contractual basis. The customer experiences this as a price rise with extra steps. Index early and transparently, or decline the business.
The third is overpromising delivery to win the quarter. In a scarcity market the penalty for a missed date is no longer a difficult conversation, it is removal from the approved vendor list at precisely the moment that list is being rewritten. Supplier lists get re-cut during shocks, and the re-cut tends to persist long after conditions normalise.
All three share a root cause: treating a change in conditions as a change in luck rather than a change in the rules. The commercial model has to be adjusted deliberately, or it will be adjusted for you by the first contract that is tested.
A short, ordered list
Audit live quotations for fixed-price exposure on long validity windows, and reissue the material ones. This is the fastest way to stop an ongoing loss and it can usually be done in a fortnight.
Produce one dated availability fact sheet per product family, with stock, lead time and delivery performance, and put it where procurement looks rather than where marketing publishes. Refresh the date monthly, because an undated claim ages into a liability.
Rescore the pipeline against the four scope areas that are actually funded, which are continuity, debottlenecking, security and storage, and reallocate effort toward the deals that sit in them rather than the ones that merely look large.
Review force majeure, escalation and index clauses in the top 20 agreements by revenue, and open the renegotiations you can see coming rather than waiting to receive them.
Finally, write down the assumption you are using about how long this lasts, and the indicator that would tell you it has ended. Nasser's two-year restocking estimate and the 2 million barrels a day of rebuild demand it implies are a reasonable base case for continued tightness. Treat that as an estimate, review it monthly, and make sure every capacity decision names which assumption it depends on.
استمع وخذها معك
هل تفضل الاستماع إلى التسجيل الصوتي، أم تحتاج إلى العرض التقديمي للمراجعة الداخلية؟ يتوفر العرض التقديمي الكامل كحلقة بودكاست وعرض شرائح قابل للتنزيل.
A long-standing customer asks you to hold your 2025 fixed price for a 2027 delivery, in a market where your freight cost has roughly doubled and your insurer has added a war risk surcharge. What do you do?
الأسئلة المتكررة
Raise the components that have genuinely risen, and index them to a published reference rather than blending them into a single new price. Freight, insurance, energy inputs and currency are the usual candidates. A transparent indexed line is easier for a procurement team to verify, approve and forecast than a wholesale increase, and it is far easier to reverse when conditions normalise, which protects the relationship on both sides of the cycle.
Delivery certainty over unit price. When an operator is losing production valued at over 100 US dollars a barrel, the cost of a late or missing item vastly exceeds any plausible saving on its purchase price. Tender scoring in these conditions shifts weight toward proven lead times, stock position, number of qualified sources, response time and supply chain transparency, with price retained as a qualifying criterion rather than the deciding one.
No one can answer this precisely, and any supplier claiming to should be discounted. The most useful anchor available is Aramco chief executive Amin Nasser's statement on 5 October 2026 that replenishing inventories while meeting demand could take up to two years once the Strait of Hormuz fully reopens, adding roughly 2 million barrels a day of rebuild demand over about 18 months. Treat that as an estimate and review it against actual inventory rebuild rates rather than against the spot price.
No, and conflating the two is the most expensive mistake available in this market. A large part of the current price is a geopolitical risk premium rather than a structural demand signal, and ING's commodities strategists described the market as pricing a significant risk premium given the volatility of the situation. Premiums unwind faster than they build, so capacity, hiring and inventory decisions should be taken against contracted scope and operator capital plans, not against the spot price.
Dated, specific and checkable facts rather than assurances. Useful content includes current quoted lead time by product family with the date it was measured, stock held and its location, the number of qualified sources for each critical input, contracted freight arrangements, and recent on-time delivery performance as a percentage against promised dates. An undated claim of good availability carries almost no weight with an experienced buyer and can actively damage credibility if it is later contradicted.
احصل على التالي إسقاط معلومات استخباراتية
انضم إلى قادة الطاقة والصناعة واحصل على معلوماتنا التسويقية، ونمو الذكاء الاصطناعي، وهيكلة الإيرادات، مباشرة وبدون حشو.
اسمك مدرج في القائمة
أهلاً بكم في موجز نمو الطاقة، تابعوا بريدكم الوارد للاطلاع على النشرة القادمة.