

Santos After the Bid: How a Failed Takeover Became a Standalone Doctrine
A 19 billion dollar consortium walked away from Santos in September 2025. A year on, the company it left behind has pushed two mega projects into production, narrowed its guidance, and started paying cash back. This is what Santos chose to do with the freedom it did not ask for, why the logic holds, and what it changes for anyone selling into it.
- The failed bid is the strategic fact, not a footnote. When the XRG, ADQ and Carlyle consortium withdrew on 17 September 2025, Santos lost the option of being acquired and kept the obligation to prove the standalone case. Everything since is an argument addressed to that audience.
- Two mega projects crossed the line. Barossa delivered first gas on 22 September 2025 and Pikka delivered first oil on 18 May 2026. The capital is spent; the question shifted from can they build it to can they run it at the cost they promised.
- The 2026 numbers describe a hinge year, not a growth year. Guidance is 99 to 105 million barrels of oil equivalent of production with sales of 102 to 108 million, and second half output is expected 20 to 30 percent above the first half as both projects ramp.
- Cash returns are the proof statement. An interim dividend of 11.6 US cents per share unfranked, about 377 million US dollars, is Santos demonstrating the thing the bid implied it could not do alone.
- Papua LNG is the next underwrite. Santos is increasing its interest while ExxonMobil takes operatorship, with final investment decision planned for the fourth quarter of 2026, inside a capital framework pegged to a 45 to 50 dollar a barrel free cash flow breakeven.
- For sellers, the buying posture has inverted. A company in build phase buys scope and schedule. A company in run phase buys uptime, unit cost and reliability. Santos crossed that line in 2026 and most vendor pitches have not.
The bid that set the clock
In 2025 Santos became the target of the largest attempted acquisition in its history. A consortium led by XRG, the international investment company of Abu Dhabi National Oil Company, alongside ADQ and Carlyle, approached the board with an indicative proposal valuing the Australian producer at roughly 19 billion US dollars. On 17 September 2025 the consortium withdrew. No deal, no break fee narrative, no second bidder.
The withdrawal matters more than the bid. An approach at that size is a market verdict that the assets are worth more than the share price implied. When the approach fails, that verdict does not disappear, it transfers. The gap between asset value and market value becomes management's problem to close, in public, on a clock set by the people who watched the bid arrive and leave.
That is the frame for everything Santos has done since. It is not a company recovering from a shock. It is a company that has been handed an explicit valuation benchmark by a credible buyer and must now demonstrate it can reach that benchmark without one. XRG's own conduct since is consistent with discipline rather than retreat: it completed the Covestro acquisition and deepened its position across all five trains at Rio Grande LNG, which tells you the consortium walked for price and structure, not for lack of appetite.
Readers tracking the acquirer side of this will find the fuller picture in our profile of what XRG is and how it invests and in the question of whether XRG behaves as private equity or as an energy operator.
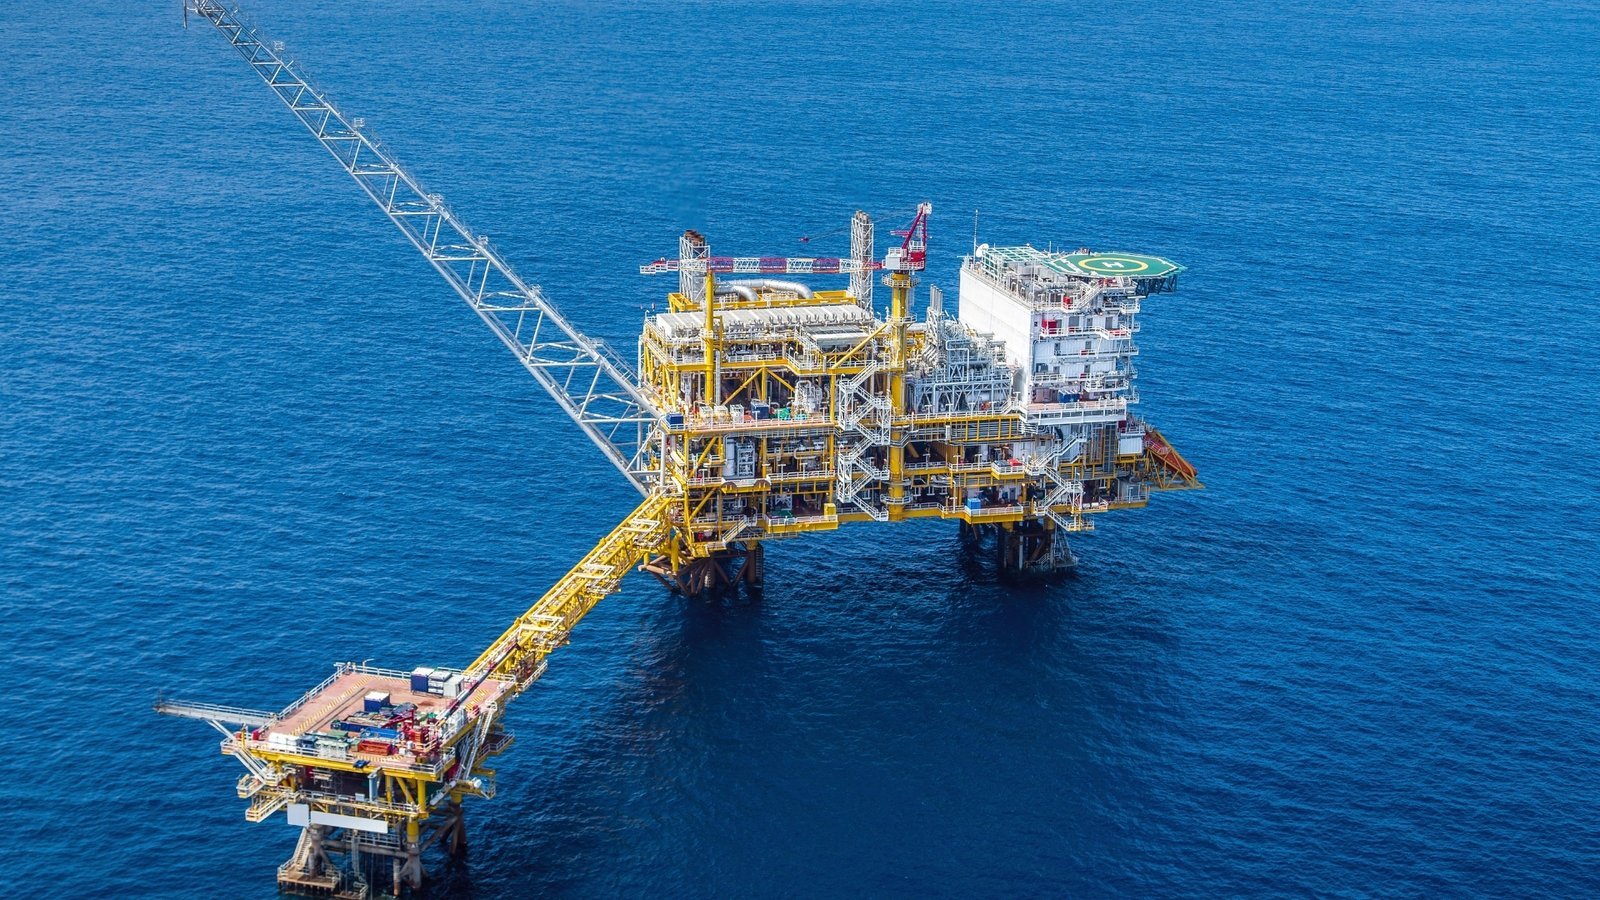 Projet 54An offshore gas production platform linked by bridge to a wellhead structure. Santos moved Barossa and Pikka from construction into ramp during 2026, shifting the company from a build phase to a run phase.
Conversion, not reinvention
The predictable response to a failed bid is a new story: a restructuring, a demerger, a pivot. Santos did the opposite. It kept the plan and changed the emphasis, moving from a narrative about building to a narrative about converting. The strategic content of 2026 is almost entirely execution.
This is a harder choice than it looks. A reinvention buys time and headlines. Conversion buys neither. It commits management to a set of numbers that can be checked quarter by quarter, and it removes every excuse that a transformation story would have supplied. Santos chose the version of the argument that can be falsified, which is the version investors believe.
Finish the build
Barossa took first gas on 22 September 2025 and Pikka took first oil on 18 May 2026. Both are now in ramp, with Barossa running around 550 million standard cubic feet a day and targeting 600 by quarter end, and Pikka Phase 1 aiming at gross plateau of roughly 80,000 barrels of oil a day in the third quarter of 2026.
Prove the unit cost
Barossa is targeted at a unit production cost below 7 US dollars per barrel of oil equivalent at plateau. A low unit cost is the only durable defence in a soft price environment, because it is the number that does not depend on the price deck.
Pay the cash back
An interim dividend of 11.6 US cents per share unfranked, about 377 million US dollars, converts the operating claim into a distribution. Cash returned is the only unambiguous evidence that a capital cycle has ended.
Underwrite the next step
An increased interest in Papua LNG, with ExxonMobil taking operatorship and final investment decision planned for the fourth quarter of 2026, extends the runway without restarting a decade of spend inside the existing capital framework.
A hinge year, read honestly
Santos guides to 99 to 105 million barrels of oil equivalent of production in 2026, with sales volumes of 102 to 108 million, and expects second half production 20 to 30 percent higher than the first half as Barossa and Pikka ramp. Chief executive Kevin Gallagher framed the half year by saying Santos was entering the second half from a stronger operating position.
Read the shape rather than the headline. A year in which the second half is materially larger than the first is not a growth year in the ordinary sense, it is a transition year in which the annual average understates the exit rate. The number that matters for 2027 is not the 2026 average, it is what the business is producing in December.
The balance sheet context is equally important. Santos reported free cash flow of about 1.8 billion US dollars for the year ended 31 December 2025 and net debt of 5,764 million US dollars. That is a company with real leverage that has just finished spending, which is precisely the condition in which a ramp either de-risks the balance sheet quickly or does not.
Note also the honest detail: the top of the 2026 guidance range was trimmed during the year. A company running a conversion argument cannot afford to hide a narrowing, because the credibility of the whole posture rests on the numbers being checkable.
| Marker | position 2026 | Pourquoi c'est important sur le plan commercial |
|---|---|---|
| Production guidance | 99 to 105 mmboe, sales 102 to 108 mmboe | Sets the operating base that suppliers are selling into, not a construction budget |
| Second half shape | 20 to 30 percent above first half | Exit rate, not the annual average, is the real 2027 starting point |
| Barossa | First gas 22 Sep 2025, around 550 mmscf/d, target 600 by quarter end | Ramp risk is now the dominant operational risk, not execution risk |
| Barossa unit cost | Targeted below 7 US dollars per boe at plateau | The defence that survives a low price deck |
| Pikka | First oil 18 May 2026, gross plateau around 80,000 bopd in Q3 2026 | Second ramp running in parallel, stretching operations capacity |
| Interim dividend | 11.6 US cents per share unfranked, about 377 million US dollars | Evidence the capital cycle has closed |
| Capital framework | Free cash flow breakeven targeted at 45 to 50 dollars a barrel | The hurdle every supplier proposal is now measured against |
| Papua LNG | Increased interest, ExxonMobil operator, FID planned Q4 2026 | The next spending window, and where new vendor positions are won |
The logic underneath the choice
There is a reading of Santos in which the standalone plan is what is left after the real plan failed. That reading is wrong, and understanding why is the useful part.
A bid arriving at a company in the final year of a heavy capital programme is arriving at the point of maximum information asymmetry. The spending is visible and the production is not yet. An acquirer at that moment is buying the completion risk cheaply. Santos' board rejecting or failing to agree that price, and then delivering first gas and first oil within eight months, is not a defensive sequence. It is the argument that the discount was mispriced, made with facts rather than with a defence document.
The second piece of logic is about capital allocation credibility. A company that has just spent heavily and then immediately spends again has no story. A company that spends, delivers, distributes, and only then commits to the next project has a repeatable framework. The ordering of Barossa and Pikka first, dividend second, Papua LNG decision third is not incidental sequencing, it is the framework being demonstrated in public.
The third piece is structural. Handing operatorship of Papua LNG to ExxonMobil while increasing economic interest is a deliberate separation of exposure from workload. Santos takes more of the value and less of the operating burden at exactly the moment its own operations team is absorbing two parallel ramps. That is a company that knows what its constraint is.
The same discipline shows up elsewhere in the sector. Compare it with Petronas choosing value over volume and with Woodside concentrating on two hubs. The common thread across all three is that the growth claim is being narrowed deliberately so the returns claim can be defended.
Build phase and run phase buy different things
This is the part most vendors will get wrong, because the account looks the same from the outside. Same logo, same procurement portal, often the same contacts. The buying logic underneath has inverted.
During a build phase, a producer buys capability and schedule. The question in the room is can you deliver this scope by this date, and price is a constraint rather than the decision. During a run phase, the producer buys unit cost, uptime and predictability. The question becomes what does this do to our cost per barrel, and every proposal is measured against a stated breakeven, in Santos' case a free cash flow breakeven of 45 to 50 dollars a barrel.
That single number is the most useful thing a seller can take from this article. It is a public hurdle rate. Any proposal that cannot be expressed as its effect on unit cost, production availability, or the reliability of the ramp is being submitted in the wrong currency.
Reprice your pitch in cost per barrel
Translate capability into its effect on operating cost or production availability. A proposal that only describes scope is asking a run phase buyer to do the translation, and they will not.
Sell into the ramp, not the plateau
Barossa and Pikka are ramping in parallel. The scarce resource at Santos right now is operational attention. Anything that reduces the load on that team during ramp is worth more in 2026 than it will be in 2028.
Track the Papua LNG window
With ExxonMobil taking operatorship and FID planned for the fourth quarter of 2026, the vendor positions on that project are being set now, and increasingly by the operator rather than by Santos.
Expect a shorter, more senior committee
A company making a public standalone argument concentrates decisions. Prepare a case that survives a finance review without you in the room, because increasingly that is where it will be read.
Three trajectories worth pricing
The standalone argument has a deadline it does not control. Roughly speaking, Santos has the period until the ramps reach plateau and the cash conversion becomes visible to prove the point. Three paths follow from there, and they are worth pricing separately rather than averaged into one forecast.
In the first, the ramps land, unit costs hold near target, the balance sheet de-levers quickly and Papua LNG takes FID on schedule. In that world Santos is re-rated on its own numbers and the 2025 bid looks like a buyer who was early rather than wrong.
In the second, the ramps land but slowly, unit costs drift, and net debt stays heavy into 2027. That is the condition in which an approach returns, and it returns from a position of greater strength because the completion risk has now been retired at Santos' expense rather than the acquirer's.
In the third, Papua LNG slips past the fourth quarter of 2026 or its economics move. That would remove the growth leg from the story and leave a cash generative but flat producer, which is a perfectly respectable business and a very different equity.
For commercial teams the practical instruction is the same across all three: do not underwrite a Santos relationship on the assumption of a new owner. In two of the three paths there is no acquirer, and in the third the acquirer inherits a supplier base that has already been rationalised by a management team proving a cost case.
Écoutez et emportez-le avec vous
Vous préférez le format audio ou vous avez besoin de la présentation pour une analyse interne ? Le compte rendu complet est disponible sous forme d’épisode de podcast et de diaporama téléchargeable.
Your largest producer account has just moved from building assets to running them. What changes first in your commercial approach?
Questions fréquemment posées
The consortium led by XRG with ADQ and Carlyle withdrew its indicative proposal on 17 September 2025. The approach had valued Santos at roughly 19 billion US dollars. A withdrawal at that stage is normally a judgement on price, structure or conditions rather than on the assets, and XRG's subsequent activity, including completing the Covestro acquisition and expanding across all five trains at Rio Grande LNG, is consistent with continued appetite deployed elsewhere.
Santos guides to 99 to 105 million barrels of oil equivalent of production in 2026, with sales volumes of 102 to 108 million barrels of oil equivalent. Second half production is expected to be 20 to 30 percent higher than the first half as Barossa and Pikka ramp up, so the December exit rate is a better guide to 2027 than the annual average.
Barossa took first gas on 22 September 2025 and has been producing at around 550 million standard cubic feet a day, targeting 600 by quarter end, with a unit production cost targeted below 7 US dollars per barrel of oil equivalent at plateau. Pikka in Alaska took first oil on 18 May 2026, with Phase 1 targeting gross plateau production of approximately 80,000 barrels of oil per day in the third quarter of 2026.
Santos is increasing its interest in Papua LNG while ExxonMobil takes operatorship. Completion is subject to conditions precedent including regulatory approvals and the project reaching final investment decision, which is planned for the fourth quarter of 2026. The commitment sits inside a capital allocation framework that targets a free cash flow breakeven oil price of 45 to 50 dollars a barrel.
There is no active proposal on the table following the September 2025 withdrawal. The realistic view is that takeover risk is now a function of execution: if the ramps land and cash conversion is visible, Santos is re-rated on its own numbers, and if they land slowly with net debt still heavy into 2027, the conditions that attract an approach reassemble. Suppliers should not underwrite the account on the assumption of a change of ownership.
It means the buying criterion has changed even though the account has not. A build phase producer buys scope and schedule; a run phase producer buys unit cost, uptime and predictability against a published breakeven. Proposals should be expressed in terms of their effect on cost per barrel or production availability, and the live commercial window for new positions is Papua LNG, where the operator is now ExxonMobil.
Obtenez la suite gouttelettes de renseignement
Rejoignez les leaders des secteurs de l'énergie et de l'industrie et recevez directement nos informations stratégiques en matière de marketing, de croissance par IA et d'architecture des revenus, sans superflu.
Vous êtes sur la liste
Bienvenue dans The Energy Growth Brief, consultez votre boîte de réception pour le prochain numéro.