

The Number That Decides Whether a Refinery Runs
A crack spread is the gap between what a refinery pays for crude and what its products sell for. It is the most quoted number in refining and one of the most widely misread, because it is a margin indicator that deliberately leaves most of a refinery's costs out.
- A crack spread compares the cost of crude going in with the wholesale value of products coming out. EIA calls it an indicator of short-term refining margin, which is a narrower claim than profit.
- The 3:2:1 spread is arithmetic, not a market quote: two barrels of gasoline plus one of distillate, converted at 42 gallons a barrel, minus three barrels of crude, divided by three.
- It excludes every refining cost except crude. EIA states plainly that crack spreads “exclude refining costs other than the cost of crude oil” and ignore the refinery's other product revenues, so a positive spread is not the same as a refinery making money.
- It moves because three separately priced commodities move. Crude is priced globally; products are shaped by local and seasonal conditions. That asymmetry is where the spread comes from.
- Which crude and which location you pick changes the answer. EIA's own worked example contrasts WTI, affected at the time by hub bottlenecks, with Louisiana Light Sweet, which was not.
It measures a gap, not a profit
The US Energy Information Administration's definition is worth reading slowly, because almost every misuse of the number comes from skipping a clause in it. A crack spread, EIA writes, “measures the difference between the purchase price of crude oil and the selling price of finished products, such as gasoline and distillate fuel, that a refinery produces from the crude oil.”
Then comes the qualification. Crack spreads “are an indicator of the short-term profit margin of oil refineries because they compare the cost of the crude oil inputs to the wholesale, or spot, prices of the outputs (although they do not include other variable costs or any fixed costs).” The parenthesis is the whole argument. Everything a refinery spends that is not crude — energy, hydrogen, catalyst, chemicals, labour, maintenance, debt service, emissions compliance — sits outside the number.
EIA is equally direct about the measure's simplicity elsewhere: crack spreads “are a simple measure based on one or two products produced in a refinery (usually gasoline and distillate fuel). They do not take into consideration all refinery product revenues and exclude refining costs other than the cost of crude oil.”
So the crack spread is a well-behaved indicator doing a narrow job: it tells you how the price of what a refinery buys is moving against the price of what it sells. That is genuinely useful, and it is not a profit and loss statement.
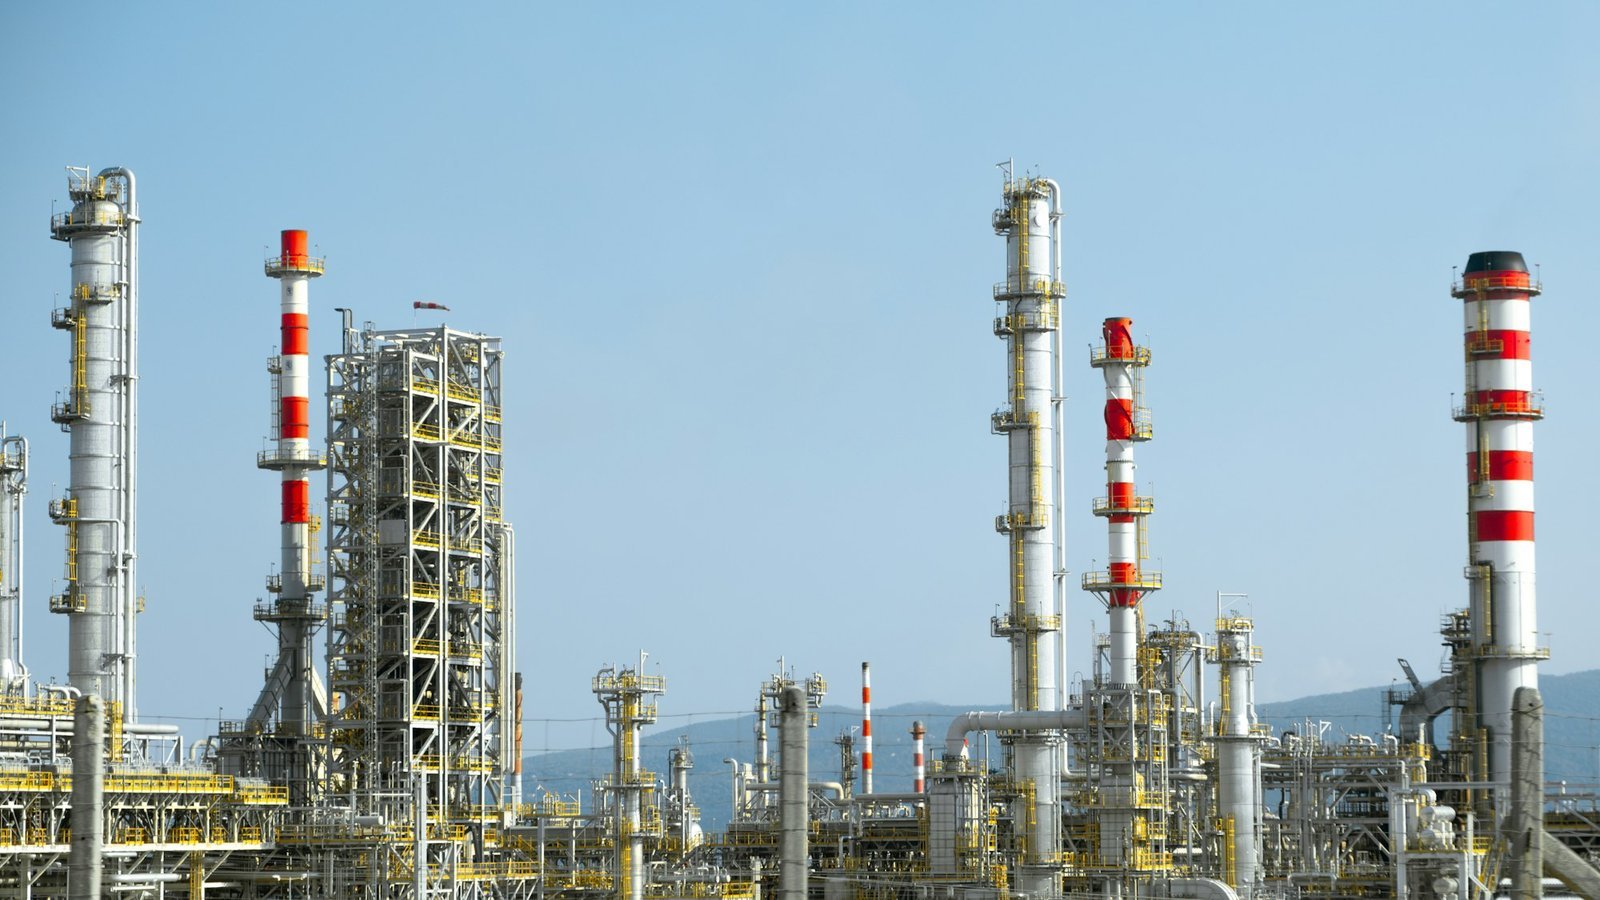 Unsplash LicenceRefinery distillation columns and red and white striped stacks against a clear blue sky.
The 3:2:1 is arithmetic you can do yourself
The 3:2:1 spread exists because a single-product spread flatters or punishes a refinery depending on which product you choose. Blending two products into one number gets closer to how a refinery actually earns. EIA explains the ratio as a yield assumption: “The 3:2:1 crack spread approximates the product yield at a typical U.S. refinery: for every three barrels of crude oil the refinery processes, it makes two barrels of gasoline and one barrel of distillate fuel.”
The calculation, in EIA's own worked example for a Gulf Coast refinery running Louisiana Light Sweet crude, runs like this. Add the spot price for two barrels of Gulf Coast conventional gasoline to the spot price for one barrel of Gulf Coast ultra-low sulfur diesel. Because product prices are quoted per gallon rather than per barrel, multiply them by 42 gallons per barrel first. Subtract the spot price for three barrels of LLS crude. Divide the result by three, and you have a spread in dollars per barrel.
Nothing about that is proprietary. Anyone with the spot series can reproduce it, which is exactly why the number became a common language rather than a vendor's product. It is also why two people can quote different crack spreads for the same day in good faith: they have chosen different crudes, different grades of gasoline or different delivery points.
The 3:2:1 is not the only ratio. EIA notes that “additional ratios used for multiple-product crack spreads include 5:3:2 and 2:1:1.” A refinery whose real yield skews towards distillate is described poorly by a 2:1 gasoline weighting, and the ratio is chosen to fit the plant rather than the other way round.
A positive spread can still be a loss-making month
Two exclusions do most of the damage when the number is quoted carelessly.
The first is cost. The only cost inside a crack spread is crude. A refinery with high energy prices, an expensive hydrogen supply, a heavy emissions bill or a large maintenance programme can be losing money through a period of healthy spreads, and the spread will not show it. This is the gap between a paper crack and a realised refining margin, and it is why operators report their own margin capture rather than pointing at the public spread.
The second is revenue. A real refinery does not make only gasoline and diesel. Jet fuel, fuel oil, asphalt, petrochemical feedstocks, lubricants and sulphur all leave the gate, and a 3:2:1 spread counts none of them. EIA's phrasing again: the measure does “not take into consideration all refinery product revenues.” For a complex refinery with deep conversion units, the spread can materially understate what the plant earns from the same barrel.
The practical rule is that a crack spread is reliable for direction and comparison, and unreliable as a level. Asking whether spreads are stronger than last quarter is a sound question. Asking what a refinery earned per barrel is a question the crack spread is not built to answer.
Three prices, three different markets
A crack spread is a difference between prices set in markets that do not share the same constraints, and that is the engine of its volatility. EIA puts the asymmetry precisely: “By comparing the price of crude oil (which is set in a global marketplace) with the price of refined products (which can be affected by local and seasonal factors), crack spreads can often give an indication of supply conditions in a given market.”
Read that sentence as a diagnostic instruction rather than a definition. A widening spread in one region while crude is flat is telling you something about that region's product supply — refinery availability, import economics, inventory cover, demand seasonality — and almost nothing about crude.
Because three interacting prices are involved, the range is wide by construction. EIA notes that “because the 3:2:1 crack spread is a product of the interplay of three commodity prices, each subject to different but interconnected supply and demand balances, the range of values can vary widely,” and that “product supply shortages resulting from serious disruptions such as hurricanes or other refinery or pipeline outages can cause large spikes of short duration.”
That last clause is the one to keep in mind whenever a spread is described as a new era. Short, severe spikes are a normal feature of the series, not evidence of a structural shift. A structural read needs a run of quarters, not a fortnight.
It is also why crude remains the dominant term in a pump price even when refining is in the headlines. EIA's own accounting of retail gasoline is blunt about the ranking: “The largest component of the retail price of gasoline is the cost of crude oil.” Refining is the volatile share, not the largest one.
The crude and the location are part of the measurement
A single-product spread, EIA explains, “reflects the difference in value between a barrel of the specified product and a barrel of crude oil,” the gasoline crack being the most common. Multiple-product spreads blend two. Either way, the choice of inputs is not a detail.
EIA's own example makes the point with a specific pair of crudes. For the crude leg, it writes, “one could use the price for either West Texas Intermediate (WTI) crude oil, which has recently been impacted by transportation bottlenecks at the main WTI market hub, or Louisiana Light Sweet (LLS) which has not been affected by bottlenecks and has continued to move closely with comparable quality global supply streams.” A WTI-based crack during a hub dislocation measures the dislocation as much as the refining margin.
The same caution applies to geography and grade. EIA names the alternatives directly: “calculating the gasoline crack spread in different locations (RBOB crack spreads in New York Harbor versus the Gulf Coast) or using different types of gasoline (conventional crack spreads versus RBOB crack spreads).” A New York Harbor 3-2-1 and a Gulf Coast 3-2-1 are different measurements of different markets, and comparing one year's figure for the first with another year's for the second produces a finding that is not there.
For anyone reading a refining claim in a trade article or a pitch deck, this is the first thing to check and the thing least often stated: which crude, which products, which delivery point, and whether the comparison holds all three constant.
It is the fastest read on your customer's appetite to spend
This section is judgement rather than published data, and it is flagged as such. Refining margins are the near-term variable in a downstream operator's world: crude slates are contracted, units are fixed, demand is seasonal, and the spread between input and output cost is what moves week to week. So it tends to lead the decisions a supplier feels.
Three of those decisions are worth watching. Run rates come first: a refinery with weak product economics trims throughput or brings a turnaround forward, which changes the timing of everything bought around that turnaround. Discretionary spend follows: reliability work, efficiency projects and digital programmes compete for attention against a margin backdrop, and a procurement conversation held through a weak quarter is a different conversation. Capital commitment comes last and most slowly, because a final investment decision reflects a view of margins over years rather than months.
The useful discipline is to treat the spread as context for timing, not as a verdict on a customer. Because the number excludes most costs and most revenues, a refiner's own reported capture can diverge sharply from the public series. The supplier who asks what the operator's own margin realisation has done, rather than quoting a regional crack back at them, is the one having the more credible conversation.
If the question you are trying to answer is when a downstream account is likely to commit, the spread is one input among several. How Project 54 builds that read into a commercial system is a longer conversation, and it starts from the operator's own disclosures rather than from a market indicator.
Écoutez et emportez-le avec vous
Vous préférez le format audio ou vous avez besoin de la présentation pour une analyse interne ? Le compte rendu complet est disponible sous forme d’épisode de podcast et de diaporama téléchargeable.
A downstream account tells you margins are tight and the project is paused. What do you do with that?
Questions fréquemment posées
It is the wholesale value of two barrels of gasoline plus one barrel of distillate, minus the cost of three barrels of crude, divided by three to express the answer per barrel. The ratio is a stand-in for refinery yield: EIA describes it as approximating “the product yield at a typical U.S. refinery.”
Because the two sides of the sum are quoted in different units. Crude trades in dollars per barrel while refined products are normally quoted in dollars per gallon, and a barrel is 42 gallons. EIA's instruction is to multiply the product prices “by 42 gallons per barrel to convert to dollars per barrel” before subtracting the crude.
No, and the distinction matters commercially. EIA says crack spreads “are often used to estimate refining margins” but “exclude refining costs other than the cost of crude oil” and ignore the refinery's other product revenues. A refiner's reported margin capture reflects its real cost base and full product slate; the crack spread does not.
Yes. EIA's own chart of a gasoline crack spread shades the positive and negative regions separately, and its text says crack spreads can be positive or negative “depending on relative product prices.” A negative spread means the wholesale value of the products in the ratio sits below the cost of the crude needed to make them, which is a signal to cut runs rather than a rounding error.
The one whose crude, products and delivery point match the market you are describing, and then the same one every time. A Gulf Coast LLS 3:2:1, a New York Harbor RBOB crack and a WTI-based spread answer different questions, and EIA itself warns that a WTI leg can carry hub transportation effects the LLS leg does not.
Most often a supply interruption rather than a change in the market's structure. EIA attributes large, short-lived spikes to “product supply shortages resulting from serious disruptions such as hurricanes or other refinery or pipeline outages.” A structural claim needs several quarters of evidence.
Obtenez la suite gouttelettes de renseignement
Rejoignez les leaders des secteurs de l'énergie et de l'industrie et recevez directement nos informations stratégiques en matière de marketing, de croissance par IA et d'architecture des revenus, sans superflu.
Vous êtes sur la liste
Bienvenue dans The Energy Growth Brief, consultez votre boîte de réception pour le prochain numéro.