Your Market Is 400 Buyers. Stop Measuring It Like a Panel.
Energy B2B marketers who measure brand at all usually measure top-of-mind awareness, which the Ehrenberg-Bass Institute has spent years arguing is the wrong instrument. The replacement, mental penetration multiplied by network size, is harder to say and easier to use. It also happens to suit energy unusually well, because a market of a few hundred named accounts can be counted rather than sampled, and because the buying situations that trigger retrieval in this sector are dated public events rather than moods.
- Top-of-mind awareness is a single, noisy number that moves with recent advertising and tells you nothing about which buying situations you are retrieved for. Professor Jenni Romaniuk of the Ehrenberg-Bass Institute has been blunt about this: there are still people out there measuring mental availability with top-of-mind awareness.
- The usable replacement is three numbers. Mental penetration, whether the brand is in memory at all. Network size, how many buying situations it is linked to among those who hold it. Mental market share, the product of the two.
- The spread between brands on these measures is large and commercially legible. In a business banking study Barclays showed 9.8 per cent mental market share, 78 per cent mental penetration and a network size of 7.9, against RBS at 4.4 per cent, 53 per cent and 5.2.
- Network size is a retention metric, not just an acquisition one. Across 17 United States business insurance products, the fewer category entry points a customer linked to a brand, the more likely they were to switch away, significant in 16 of the 17, with each additional link estimated to cut defection probability by about 5 per cent.
- Category entry points are elicited with a structured prompt set, the Ws: when, where, while, with what, why, how feeling, and with or for whom. Romaniuk recommends narrowing to a long shortlist of five to eight, chosen on credibility, competitiveness and commonality.
- In energy the entry points are dated and public. A final investment decision, a planned turnaround, a framework agreement expiry, a compliance deadline, an incumbent failure and a capacity constraint are all observable, which means the survey can be validated against events rather than opinions.
- Small universes are a measurement advantage, not an obstacle. If the relevant buying population is a few hundred named organisations, a census removes sampling error entirely, and a quarterly tracker that was never statistically powered becomes an annual census that is.
- Mental availability cannot rescue an ineligible supplier. If you are not in the buyer's qualification system you cannot receive the tender, so eligibility is a floor beneath the brand measure rather than an alternative to it.
The instrument, not the effort
Two failure modes dominate. The first is measuring nothing, on the reasonable-sounding grounds that a market this small and this relationship-driven cannot be surveyed. The second is measuring awareness, usually unprompted and top-of-mind, in a quarterly tracker with a sample too thin to carry the conclusions drawn from it.
The second is the more expensive error, because it produces a number that moves. Top-of-mind awareness responds to recent activity, which makes it look responsive and makes it useless as a measure of durable memory. It also collapses the only distinction that matters commercially. Being remembered is not one thing. Being remembered when a turnaround is being scoped and being remembered when a framework is being renewed are different memories, and a brand can hold one without the other.
Jon Lombardo, when he led research at the LinkedIn B2B Institute, put the underlying point in a sentence that survives the slogan test: memories generate sales, clicks don't generate sales. His colleague Peter Weinberg was more direct about the state of the discipline, calling measurement probably the biggest gap in brand marketing right now. That gap is wider in energy than almost anywhere, because the deal sizes are large enough to justify proper measurement and the buying populations are small enough that nobody bothers.
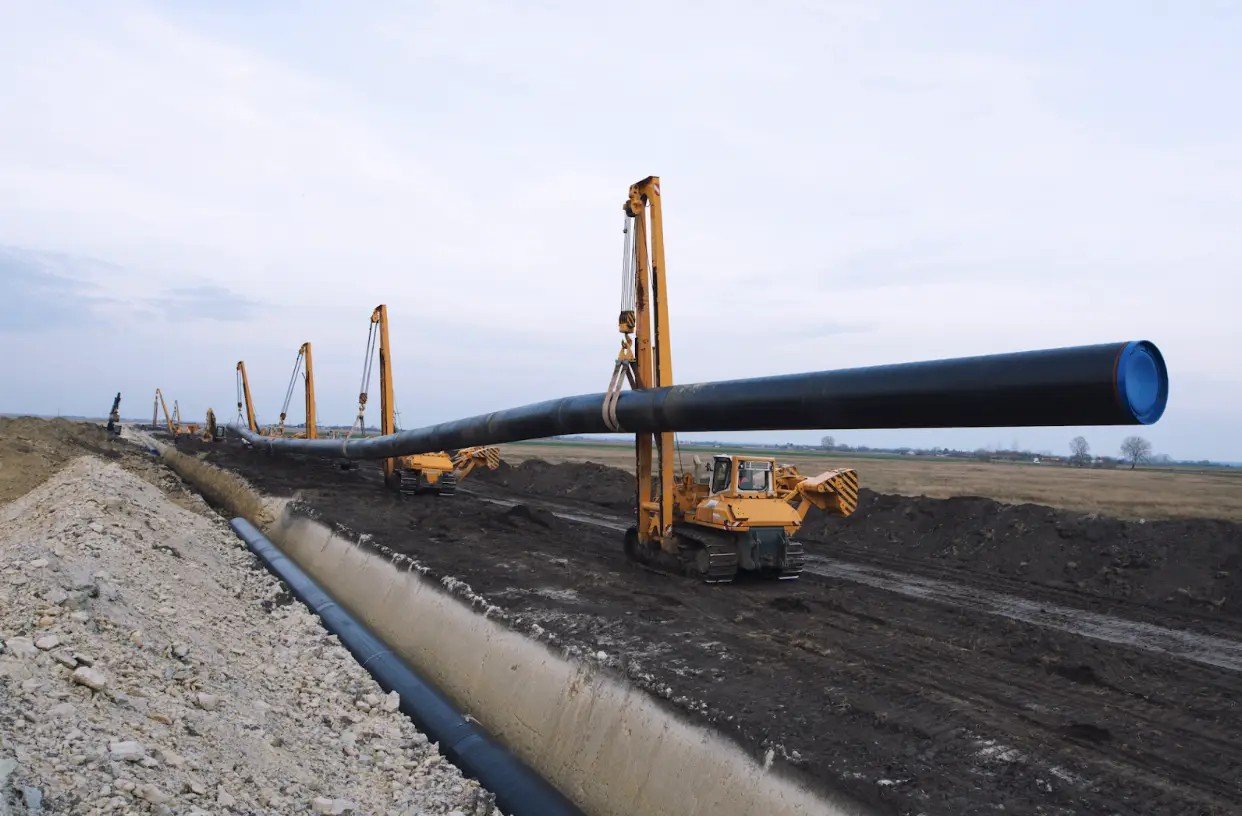 Projet 54Pipeline construction, sections lowered into a prepared trench. Mental availability is built the same way, laid in advance of the demand it will carry, and measured by whether it is there when the flow starts.
Three numbers, one of them a product of the other two
Romaniuk's framework, set out in Category Entry Points in a B2B World, published by the B2B Institute at LinkedIn in June 2022, replaces awareness with a structure. Buyers are shown a set of buying situations and asked, for each, which brands come to mind, in a free-choice format that lets them pick as many or as few as they like, including none.
From the resulting matrix come three measures. Mental penetration is the proportion of buyers who link the brand to at least one situation. Network size is the average number of situations linked, among those buyers who linked it at all. Mental market share is the two multiplied, and expresses the brand's share of all brand-to-situation links in the category.
The reason this works better than awareness is that it is diagnostic. A brand with high penetration and a small network is known but narrow, retrieved for one situation and invisible for the rest, which is a messaging problem. A brand with a large network among few buyers is well understood by a minority, which is a reach problem. Awareness cannot tell those apart, and they call for opposite responses.
The method also sets a threshold for significance rather than leaving interpretation to taste. Expected values are computed row by column across the matrix, and deviations of five percentage points or more are treated as a mental advantage or disadvantage for that brand on that situation.
| Mesure | Ce que cela répond | How to collect it | Cadence |
|---|---|---|---|
| Mental penetration | Are we in memory at all, for anyone | Census survey of the named buying universe, free-choice brand picking across the entry point set | Annual |
| Network size | How many buying situations retrieve us, among those who hold us | Same instrument, averaged over buyers with at least one link | Annual |
| Mental market share | What share of all brand-to-situation links in the category are ours | Penetration multiplied by network size | Annual |
| Entry point advantage | Which specific situations we over or under-index on | Deviation from the expected value, five percentage points or more | Annual |
| Bid invitation rate | Is the memory converting into procedural access | Count of invitations to tender received, by account, from CRM | Quarterly |
| Qualification currency | Can we legally be retrieved at all | Status in each buyer's qualification system | Quarterly |
Dated events, not moods
Consumer category entry points are often situational and emotional: when I am in a hurry, when I want to treat myself. Business ones in the published research are closer to circumstances: when we are opening a new office, when a contract is up. Energy is further along that spectrum again. The buying situations that matter are specific, dated and usually a matter of public record.
A workable starting set, to be narrowed to five to eight on Romaniuk's three criteria of credibility, competitiveness and commonality: when a project takes a final investment decision, when a planned turnaround or shutdown is being scoped, when a framework agreement is approaching expiry, when a regulatory deadline forces a change, when an incumbent supplier fails or is consolidated away, when capacity on a critical item is constrained, when a local content requirement has to be met, and when an asset changes hands.
The advantage of this list is that it is checkable. We have argued before that intent in energy is causal and public rather than behavioural, because a sanction or a contract expiry is the trigger and the research activity follows it. The same logic applies to measurement. If your mental market share is strongest on turnarounds and weakest on final investment decisions, that is a claim you can test against which tenders you were actually invited to, which is not available to a brand tracker built on attitudes.
Romaniuk's guidance on cadence fits this too. She suggests the strategic review of entry points may need updating only once a year or every two years, unless above-the-line activity is heavy. Energy buying situations change on the timescale of regulation and capital cycles, not quarters.
Count it instead of sampling it
The objection to brand measurement in energy is always sample size, and it is a real objection to the wrong design. A panel-based tracker needs a fresh random sample each wave, and in a category with a few hundred relevant organisations there is no such thing as a fresh random sample. You end up surveying the same people, or people who are not buyers at all.
The design that works is a census. Enumerate the buying universe as named organisations and named roles inside them, then attempt the whole list. The published B2B entry point studies ran on samples in the hundreds, 606 business insurance customers and 609 business banking customers for example, which is the same order of magnitude as the entire addressable population for many energy suppliers.
How small is small? It depends on the segment, and the honest answer is that most suppliers have never counted. As a reference point, the Energy Information Administration counted eight operational LNG export terminals in the United States in February 2026. A supplier whose product sells into that segment has a buying universe measured in dozens of organisations, not thousands. Scale that to a few hundred when you add Europe and Asia, multiply by the six to ten people who sit on a typical energy buying committee, and the total named population is in the low thousands.
That is a population you can attempt in full. A census removes sampling error by construction, makes non-response the only bias worth managing, and turns a defensive conversation about statistical power into an operational one about coverage. It also produces something a tracker never does: a named list of accounts where you have no mental penetration at all.
The floor beneath the measure
No, and this is the correction energy demands of the general theory. In most categories being remembered is sufficient to be considered. In energy it is not, because consideration runs through a qualification system before it runs through a person.
Operators qualify suppliers through shared industry databases and their own systems, and a supplier who is not registered and current cannot receive the invitation to tender however well regarded they are. Equinor's own supplier guidance makes the converse point too, that registering in its qualification systems does not guarantee work. Qualification is necessary and not sufficient. Mental availability is the sufficient part, and it only pays out above the floor.
Practically, this means the measurement programme has two tiers. Qualification currency is a quarterly operational check with a binary answer per buyer. Mental availability is an annual strategic measure. Reporting them together prevents the most common misdiagnosis in this sector, which is treating a procedural exclusion as a brand weakness and spending against it.
Breadth of memory is a retention asset
The finding that should change budget conversations is about customers you already have. In the insurance analysis, across 17 products, the fewer entry points a customer linked to their own provider, the higher their stated probability of switching away. The relationship held in 16 of the 17 products, with an average regression slope of minus 0.2, and Romaniuk estimates that each additional entry point lowers defection probability by roughly 5 per cent from a baseline of 4.4 for customers linked on nought to two points.
The distribution is just as telling. For State Farm, a brand with 25 per cent penetration in that study, 40 per cent of decision makers linked it to six or more entry points, against 21 per cent for Hartford and 8 per cent for Hanover.
Translate that into a framework-agreement market. A supplier who is remembered only for the thing they currently supply is structurally exposed at renewal, because the renewal conversation is the one moment the buyer reconsiders the whole scope. A supplier remembered across six or eight buying situations is not just better placed to win new scope, they are measurably harder to displace in the scope they hold. That reframes brand spend from an acquisition cost to a defence of existing revenue, which is a far easier case to make to a finance director in a sector where renewal revenue dominates.
One caveat worth stating. These figures come from business insurance and business banking, not from energy. The direction of the relationship is well evidenced, the magnitudes are not transferable, and anyone quoting the 5 per cent figure as an energy number is overreaching. Establishing the energy coefficient is exactly what a census-based programme would produce after two or three annual waves.
Annual census, quarterly behaviour
The programme that fits a normal energy marketing function has four parts and one analyst.
First, enumerate the universe once: named accounts, named roles, with owners in the commercial team. Second, agree five to eight entry points using the Ws prompt set with sales and bid teams, which also has the side effect of being the most useful workshop most commercial teams will run that year. Third, field a short free-choice instrument annually across the whole list, accepting that response rates in this sector are low and that non-response management is the real craft. Fourth, pair it quarterly with two behavioural counts you already hold, bid invitations received and qualification status.
Judge the programme on the behavioural numbers moving in the direction the mental ones predicted. If mental market share rises on turnaround-related entry points and turnaround tender invitations follow over the next two cycles, the instrument is working. If mental measures rise and invitations do not, you have either a qualification problem or an entry point set that does not reflect how buying actually starts. Both are findings worth having, and neither is available from an awareness score.
Écoutez et emportez-le avec vous
Vous préférez le format audio ou vous avez besoin de la présentation pour une analyse interne ? Le compte rendu complet est disponible sous forme d’épisode de podcast et de diaporama téléchargeable.
Your annual census shows mental penetration of 61 per cent across your named buying universe but a network size of 2.1, against a category average of 4.6. What does that pattern tell you to do first?
Questions fréquemment posées
Mental market share is a brand's share of all brand-to-buying-situation links in a category. It is calculated as mental penetration, the proportion of buyers who link the brand to at least one buying situation, multiplied by network size, the average number of situations those buyers link it to. It was set out by Professor Jenni Romaniuk of the Ehrenberg-Bass Institute.
A category entry point is a buying situation that causes someone to think of a category and retrieve brands from memory. They are elicited using a structured prompt set covering when, where, while, with what, why, how feeling, and with or for whom. In energy they tend to be dated events such as a final investment decision, a turnaround, a framework expiry or a regulatory deadline.
Because it collapses every buying situation into one number and responds to recent advertising rather than durable memory. It cannot distinguish a brand that is known by many buyers for one thing from a brand known by fewer buyers for many things, which are different problems requiring opposite responses.
Yes, and more reliably than in large markets, provided the design changes. A small universe should be surveyed as a census rather than sampled, which removes sampling error entirely and leaves non-response as the only bias to manage. The published B2B entry point studies ran on samples of around 600, which is the same order of magnitude as the whole addressable population for many energy suppliers.
No. Qualification is a procedural floor. A supplier who is not registered and current in a buyer's qualification system cannot receive the tender regardless of how well the brand is remembered, so qualification status should be tracked quarterly alongside the annual brand measure.
Obtenez la suite gouttelettes de renseignement
Rejoignez les leaders des secteurs de l'énergie et de l'industrie et recevez directement nos informations stratégiques en matière de marketing, de croissance par IA et d'architecture des revenus, sans superflu.
Vous êtes sur la liste
Bienvenue dans The Energy Growth Brief, consultez votre boîte de réception pour le prochain numéro.