

Channel and Partner Marketing in Energy B2B
Most energy suppliers do not sell to the operator. They sell through an EPC contractor, an OEM, a systems integrator or a distributor, and they only get that far if they already sit on an approved vendor list. Forrester's standing estimate is that roughly 75 percent of world trade moves indirectly. In energy the indirect route is not a channel strategy, it is the default structure of the market. Here is how the gates actually work, and how to market through them.
- Energy procurement is gated twice. The operator's approved vendor list and local content score decide whether you are allowed to bid at all, and the EPC contractor's specification decides whether you are actually named in the package. Clearing one gate and not the other produces pipeline that never converts.
- Local content is now a scored, weighted commercial instrument, not a compliance footnote. Saudi Aramco reported reaching 70 percent local content in goods and services procurement in February 2026, with a 75 percent target by 2030, and ADNOC has committed AED 220 billion into the UAE economy through ICV over five years.
- Buying groups have grown, not shrunk. Forrester's State of Business Buying 2026 puts the typical purchase at 13 internal stakeholders plus 9 external influencers, with procurement acting as a decision maker in 53 percent of cycles. External influencers are exactly where partners sit.
- The decision is made earlier than most vendors assume. 6sense found 94 percent of buying groups have a preferred vendor in mind before they contact anyone, and that vendor wins around 77 to 80 percent of the time. Partner mindshare is therefore an upstream investment, not a closing tactic.
- The channel's share of spend is not automatically rising. Canalys and Omdia measured partner delivered IT spend at about 70 percent in 2025, down from 71 percent in 2024 and 73 percent in 2023, as marketplaces and direct billing take share. Assume the route has to be earned and re-earned.
- Machine readable proof is becoming the admission ticket. Gartner forecasts that by 2028 around 90 percent of B2B buying will be intermediated by AI agents, with more than 15 trillion dollars flowing through agent exchanges. Certifications, ICV scores and product data that a partner cannot extract cleanly will not survive that filter.
The operator specifies, the contractor buys
Energy capital spending is large, concentrated and executed through intermediaries. The IEA's World Energy Investment 2026 put global energy investment at about 3.4 trillion dollars, up 5 percent, split roughly 2.2 trillion dollars clean and 1.2 trillion dollars fossil, with electricity accounting for close to 60 percent of the total. Very little of that money is paid by an operator directly to a component or software vendor. It is paid to an engineering, procurement and construction contractor, a drilling contractor, an OEM package supplier or a licensed service company, and it is those organisations that place the purchase orders.
That creates a split between who decides and who buys. The operator's engineering function writes the specification and maintains the approved vendor list. The EPC contractor prices the package, manages the schedule and selects from whichever suppliers are both approved by the client and acceptable to its own supply chain team. A vendor can be technically preferred by the operator's engineers and still lose the order because it never reached the contractor's bid list, or be favoured by the contractor and excluded because it is not registered with the client.
Forrester has long argued that the indirect route dominates commerce generally. Jay McBain, then leading Forrester's research for global channels, alliances and partnerships, framed it bluntly in a 2020 interview: "There's a lot more partnerships than people think. 75% of all world trade goes indirectly. So you look at the $80 trillion GDP of the world, and 60 trillion of it goes indirectly." Energy is at the extreme end of that distribution because of the scale of the projects and the liability attached to them.
A note on sizing, because the numbers circulating are not reliable. Public estimates of the engineering, procurement and construction market come only from commercial report vendors and diverge wildly. For oil and gas EPC in 2025 alone, published figures range from roughly 55 billion dollars (IMARC) to about 62 billion dollars (DataM Intelligence) to nearly 200 billion dollars (market.us), a spread of more than three times driven by incompatible scope definitions. Treat all of those as vendor estimates rather than facts, and anchor on the IEA capex figure instead.
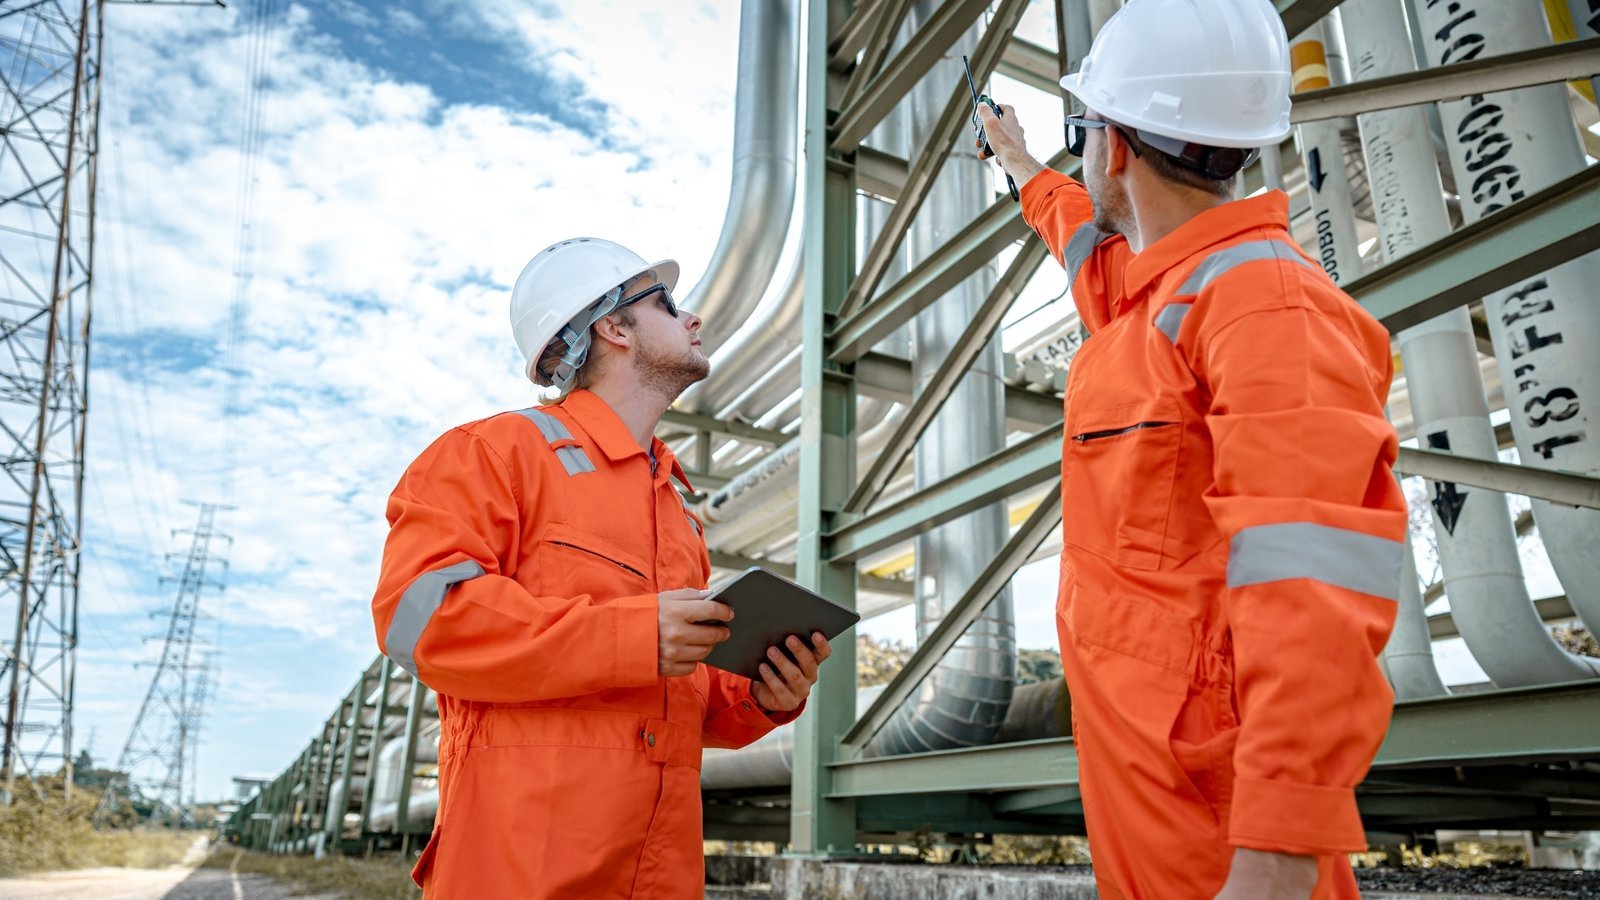 Project 54Two engineers reviewing work on a tablet at an operating energy site. In energy B2B the specification is usually agreed between an operator's engineer and a contractor's engineer, long before a vendor's sales team is invited into the conversation.
Registration, local content score, then specification
The first gate is registration and prequalification with the operator. This is administrative, slow, and non-negotiable. QatarEnergy, for example, requires a supplier to obtain a SAP Vendor Code through its Mushtaryat vendor registration portal before it can even receive an invitation to tender. Petrobras runs the equivalent through its Petronect supplier registry, where qualification by family of interest produces a Cadastral Registration Certificate that gates bidding.
The second gate is the local content score. This is where the commercial weight now sits, because these schemes are scored and weighted directly into bid evaluation. Saudi Aramco's iktva programme builds a supplier score from localised goods and services, salaries paid to Saudi nationals, training and development, supplier development spend and research, divided by company revenue, with an export revenue factor on top. ADNOC's In-Country Value programme issues one certificate per legal entity, audited against IFRS accounts by approved certifying bodies, and that certificate travels across the unified National ICV Program. QatarEnergy's Tawteen has applied an ICV policy to bid evaluation since July 2020.
The numbers show how serious this has become. Aramco reported in February 2026 that iktva had reached its 70 percent local content target in goods and services procurement, contributed more than 280 billion dollars cumulatively to Saudi GDP, attracted 9 billion dollars of inward investment across 350 investments from 35 countries, and supported over 200,000 jobs, with a 75 percent target set for 2030. Amin H. Nasser, President and Chief Executive Officer of Saudi Aramco, described the logic in that release: "iktva is a core pillar of Aramco's strategy to build a competitive national industrial ecosystem that supports the energy sector, while also enabling broader economic growth and creating thousands of job opportunities for Saudi nationals. By localizing the supply chain, iktva ensures operational reliability while mitigating disruption."
ADNOC has attached similar weight to ICV, reporting AED 65.7 billion awarded to around 400 local suppliers in the first half of 2025 and committing AED 220 billion into the UAE economy through ICV over a five year period against AED 551 billion of capital spending. For a supplier, that means the partner you choose in market is not a distribution convenience, it is a scoring input. We covered the mechanics of this in detail in iktva and ICV, local content in the GCC and the arithmetic in how an iktva or ICV score is calculated.
The third gate is the specification itself. Being registered and well scored gets you the right to be considered. Being named in the EPC contractor's package, or written into the operator's technical specification as an approved make, is what actually produces revenue. These are two separate lists maintained by two separate organisations with different incentives, and a marketing programme that treats them as one will consistently misread its own funnel.
| Gate | Who controls it | What it requires | What marketing must supply |
|---|---|---|---|
| Vendor registration | Operator or NOC supply chain | Legal entity, financials, HSE record, portal registration (Mushtaryat, Petronect, ADNOC Supplier Hub) | Accurate, current, machine readable company and product data; owned registration calendar |
| Local content score | Operator scheme office and accredited certifiers | Audited ICV or iktva certificate, localisation footprint, national hiring and training spend | Evidence pack, partner structure that improves the score, case proof of local delivery |
| Technical prequalification | Operator engineering | Standards conformance, testing records, reference installations in comparable duty | Specification ready datasheets, third party certification, reference list by duty and region |
| EPC or OEM bid list | Contractor supply chain and proposals team | Commercial terms, lead time, schedule risk, prior performance with that contractor | Partner facing enablement, quick turn quotations, co-branded proof for the contractor's own bid |
| Named specification | Operator engineering plus contractor design | Being written in as an approved make or equivalent | Early technical influence, standards participation, education content aimed at specifying engineers |
Bigger committees, earlier decisions, external voices
The buying committee has grown. Forrester's State of Business Buying 2026 found that a typical business purchase now involves 13 internal stakeholders plus 9 external influencers, that procurement acts as a decision maker in 53 percent of buying cycles, and that 78 percent of purchases worth 10 million dollars or more involve a trial. Barbara Winters, VP and Principal Analyst at Forrester, put the implication for marketers this way: "As buying groups expand and decision cycles grow, B2B marketers must develop dynamic, role-specific insights that capture how buyers evaluate risk, seek information, and define success for their business purchase."
Those 9 external influencers are the point. In energy they are not anonymous advisers, they are the EPC's lead process engineer, the OEM's application specialist, the certifying body, the owner's engineer and the incumbent service contractor. They are reachable, nameable and mostly ignored by vendor marketing that is aimed exclusively at the operator's logo.
Gartner's research points the same way on complexity. In a survey of 632 buyers, Gartner found buying groups ranging from five to 16 people across as many as four functions, with 74 percent showing unhealthy conflict during the decision process. Delainey Kirkwood, Principal Research in the Gartner Sales Practice, summarised it: "Buying groups are more diverse than ever, ranging from five to 16 people across as many as four functions. Each member may have differing priorities and opinions."
Timing is the harder lesson. 6sense's 2025 Buyer Experience Report, based on more than 4,000 buyers, found that 94 percent of buying groups have a preferred vendor in mind before they make contact, and that preferred vendor goes on to win between 77 and 80 percent of the time. Kerry Cunningham, Head of Research and Thought Leadership at 6sense, stated the consequence directly: "Buyers are choosing a preliminary winner much earlier than they have in the past… The real urgency for revenue teams is to influence those early journeys before buyers reach out." The same report measured the research to seller engagement split shifting from roughly 70/30 to 60/40, with the cycle shortening from 11 months to 10.
Read those two findings together and partner marketing stops being a distribution question. If the preference is formed before contact, and a partner is inside the room when it forms, then partner mindshare is the earliest and cheapest point of leverage available to an energy vendor. This is the same logic we applied to direct demand in buyer intent data and buying signals in energy B2B, applied one layer further upstream.
Three audiences, one evidence base
A functioning programme addresses three audiences with one shared evidence base. The first is the specifying engineer at the operator, who needs standards conformance, duty specific reference installations and comparison material that is honest about where the product does not fit. The second is the partner's own commercial team, who need to win their bid, which means they need quotation speed, lead time certainty, co-brandable proof and clean commercial terms far more than they need brand storytelling. The third is the partner's technical team, who need training, configuration tools and application support so they specify you correctly rather than defensively.
The practical build is unglamorous. Maintain a registration and certification calendar as a marketing owned asset, because an expired ICV certificate removes you from the bid list as effectively as losing on price. Build a partner portal that holds current datasheets, certificates, drawings and a configurator rather than a PDF library. Produce deal registration that is fast enough that partners actually use it, because unregistered partner activity is invisible in your pipeline and will make the whole motion look unprofitable.
Measurement is where most energy channel programmes fail. Partner sourced revenue, the orders a partner brought you, is easy to count and badly understates the truth. Partner influenced revenue, the deals where a partner shaped the specification or the shortlist without transacting, is where the value sits and is almost never instrumented. Forrester's State of B2B Partner Ecosystems 2025 found 67 percent of B2B firms expect partner transacted revenue to grow by more than 30 percent year on year, and about two thirds expect partner influenced revenue to grow at that rate too. If you cannot see the second number you cannot defend the budget that produces it. The instrumentation problem is a revenue operations problem, which we set out in revenue operations for energy B2B.
One caution against assuming the channel only grows. Canalys and Omdia's Channels and Ecosystems Landscape 2025 measured partner delivered spend at roughly 70 percent of a 5.3 trillion dollar IT market, down from 71 percent in 2024 and 73 percent in 2023, as hyperscaler marketplaces bill customers directly. The energy equivalent is the operator digital supplier hub and the procurement portal. The indirect route is durable in energy because of prequalification and liability, but the share of value captured by any individual intermediary is not guaranteed.
Qualify the gate, not the logo
Track registration status, ICV or iktva score and prequalification expiry per operator as pipeline stages in their own right. A named account you cannot legally bid is not an opportunity.
Arm the partner's bid
Partners do not need your brand story, they need to win a package. Quotation turnaround, lead time certainty, co-brandable technical proof and clean terms are the marketing assets that move share.
Influence the specification early
Preference forms before contact. Standards participation, engineer facing education and duty specific reference evidence are how you get written in rather than bid against.
Instrument influence, not just source
Partner sourced revenue undercounts the motion. Capture partner influence on shortlist and specification, or the programme will look unprofitable and get cut.
Machine mediated qualification, human closing
Two forecasts point in apparently opposite directions and both are probably right. Gartner predicted in October 2025 that by 2028 around 90 percent of B2B buying will be intermediated by AI agents, with more than 15 trillion dollars of spend flowing through agent exchanges. Gartner has separately predicted that by 2030, 75 percent of B2B buyers will prefer sales experiences that prioritise human interaction over AI.
The resolution is that the two layers separate. Qualification, comparison and shortlisting move toward machines. Negotiation, risk allocation and commitment stay human. For an energy vendor selling indirectly, that maps neatly onto the gate structure already described: the registration, certification and specification-fit layer becomes machine mediated and therefore depends entirely on whether your certificates, product data and ICV status exist as structured, verifiable data rather than as prose in a brochure. The contractor relationship, the schedule risk conversation and the commercial terms remain a human business.
This is the same argument we made about direct selling in AI buying agents and energy B2B, and it lands harder in the channel because a partner is already a compression layer. A partner who cannot extract your lead time, certification scope and compliance status quickly will quote the competitor who made it easy, and an agent operating on the partner's behalf will do the same thing faster and without apology.
The strategic conclusion is unchanged in shape but sharper in urgency. In energy the route to the operator runs through organisations you do not control, past gates you cannot bypass, into decisions that are substantially made before anyone contacts you. Partner marketing is the discipline of being present, credible and easy to specify at every one of those points. It is engineered, not assumed.
Listen & take it with you
Prefer audio, or need the deck for an internal review? The full briefing is available as a podcast episode and a downloadable slide presentation.
Where does your energy channel programme currently break down?
Frequently asked
Partner sourced revenue is business a partner brought to you and usually transacted. Partner influenced revenue is business you won directly, or through another route, where a partner shaped the specification, the shortlist or the technical decision without taking the order. In energy the influenced number is typically the larger and more strategic of the two, because EPC contractors and OEMs often shape what gets specified without ever buying the item themselves. Forrester's State of B2B Partner Ecosystems 2025 found around two thirds of B2B firms expect partner influenced revenue to grow by more than 30 percent year on year, so failing to instrument it understates the programme materially.
An approved vendor list, sometimes called an AVL or a supplier register, is the set of suppliers an operator permits its own teams and its contractors to buy from for a given category. Entry normally requires formal registration through the operator's portal, submission of legal and financial records, an HSE and quality audit, technical prequalification against the relevant standards, and increasingly a local content certificate. QatarEnergy requires a SAP Vendor Code obtained via its Mushtaryat portal before a supplier can receive tender documents, and Petrobras issues a Cadastral Registration Certificate through Petronect. The process takes months, so it should be planned as a lead time rather than reacted to when an opportunity appears.
They are weighted into bid evaluation, which means a higher score can beat a lower price. Saudi Aramco's iktva score combines localised goods and services, salaries to Saudi nationals, training and development, supplier development spend and research, divided by company revenue, with an export factor. ADNOC's ICV certificate is issued per legal entity against audited IFRS accounts by approved certifying bodies and is recognised across the unified National ICV Program. Aramco reported reaching 70 percent local content in goods and services procurement in February 2026 with a 75 percent target for 2030, so the direction of travel is toward more weight, not less. For a foreign supplier the practical route to a better score is usually local manufacturing, local hiring or a structured joint venture with a local partner.
In most energy categories it is not a binary choice, because the operator specifies and the contractor buys. The workable model is to market to the operator's engineering function so that you are specified, and to enable the EPC contractor, OEM or distributor so that you are commercially easy to include in their package. Selling exclusively direct tends to produce technical preference with no order path. Selling exclusively through partners tends to produce price led commoditisation because nobody has secured the specification. The exception is where the operator buys directly from a framework agreement, in which case the direct route dominates and the partner layer is mostly logistics.
It is splitting the process in two. Gartner forecasts that by 2028 around 90 percent of B2B buying will be intermediated by AI agents, with more than 15 trillion dollars flowing through agent exchanges, which pushes qualification, comparison and shortlisting toward machines. Gartner separately forecasts that by 2030, 75 percent of B2B buyers will prefer sales experiences that prioritise human interaction over AI, which keeps negotiation and risk allocation human. For energy vendors the practical effect is that certifications, product specifications and local content status need to exist as structured, verifiable data that a partner or an agent can extract in seconds, while the contractor relationship itself remains a human commercial exercise.
Get the next intelligence drop
Join energy and industrial leaders getting our marketing, AI-growth and revenue-architecture intelligence, direct, no filler.
You're on the list
Welcome to The Energy Growth Brief, watch your inbox for the next dispatch.